

1. What Is the Omni‑Channel Maturity Model?
The Omni‑Channel Maturity Model is a structured framework for assessing how effectively a company integrates customer experience, data, operations, and technology across channels—stores, ecommerce, mobile, marketplaces, contact centers, field sales, and partners. Rather than focusing on any single touchpoint, it evaluates the enterprise’s ability to deliver a coherent, continuous journey for customers while managing economics (price realization, cost‑to‑serve, inventory turns) at scale.
In Marketing—specifically within market, portfolio, and environmental analysis—the model gives executives and consulting teams a common language to benchmark current capabilities, identify gaps that limit growth or margin, and prioritize investments. It’s widely used in transformation programs because it turns a sprawling set of cross‑functional issues into a practical roadmap tied to outcomes: higher conversion, better loyalty, lower leakage, and improved inventory productivity.
At its core, the Omni‑Channel Maturity Model is a capability and operating‑model framework. It helps you answer: How integrated are our channels from a customer perspective? Do our data and systems support this integration? Are our pricing, inventory, fulfillment, and service policies economically coherent across routes‑to‑market? It’s commonly used by consultants as the diagnostic spine for omnichannel strategy and execution.
2. Origin and Background
Origin: Unknown; in use since at least the early 2010s. Multiple variants have been published by research firms and consultancies, each with their own labels and maturity levels.
Why it was created: As digital and physical channels proliferated, companies struggled with fragmented experiences, siloed data, and conflicting incentives. Executives needed a way to measure where they stood, set a target state, and sequence the hard work of integration across marketing, merchandising, supply chain, technology, and finance.
How it became widely known: Through industry research, business school teaching on digital transformation, and practical adoption in retail, consumer goods, financial services, and B2B distribution. “Omnichannel,” “unified commerce,” and “experience orchestration” became mainstream as leaders sought to connect journeys end‑to‑end.
3. How the Omni‑Channel Maturity Model Works
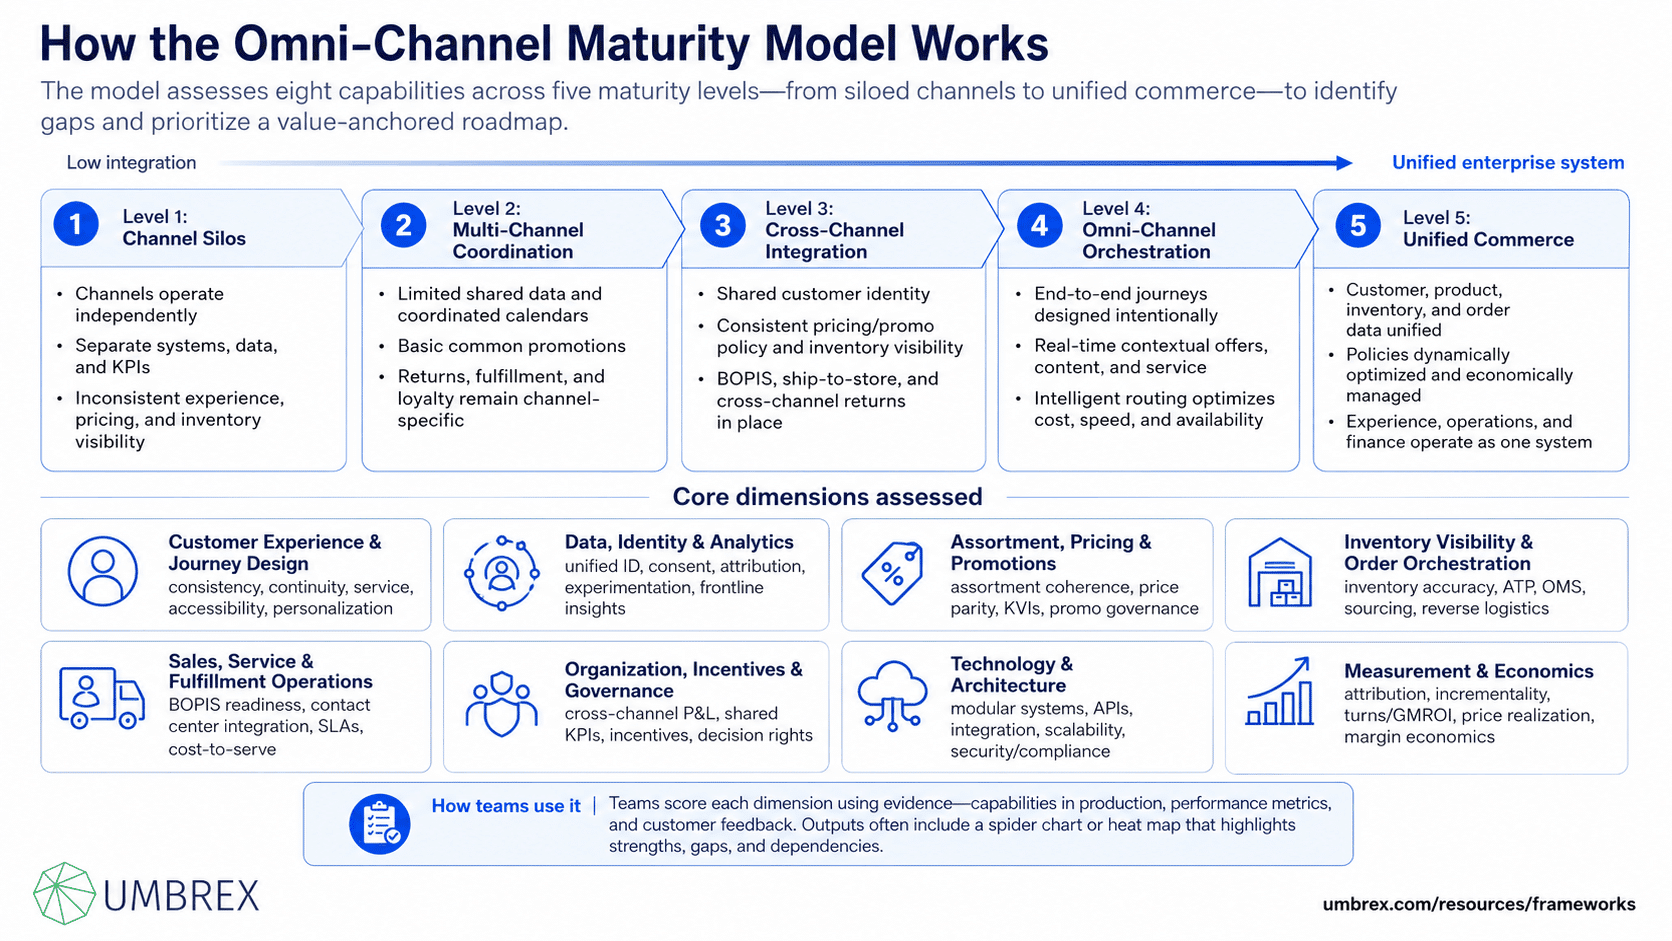
The model evaluates maturity across levels and dimensions. While labels vary, the underlying logic is consistent: move from siloed channels to integrated experiences and economics, enabled by unified data, policies, and technology.
Typical maturity levels:
- Level 1: Channel Silos — Each channel (store, web, contact center, partner) operates independently with separate systems, data, and KPIs. Customer experience is discontinuous; pricing, promotions, and inventory visibility are inconsistent.
- Level 2: Multi‑Channel Coordination — Channels share limited data and plan calendars together, but integration is shallow. Basic capabilities (e.g., common promotions) exist; returns, fulfillment, and loyalty are still channel‑specific.
- Level 3: Cross‑Channel Integration — Shared customer identity, consistent pricing/promo policy, and inventory visibility across channels. Foundational services (buy‑online‑pickup‑in‑store, ship‑to‑store, cross‑channel returns) are in place, though not yet optimized for cost or speed.
- Level 4: Omni‑Channel Orchestration — Journeys are designed end‑to‑end. Offers, content, and service adapt to customer context in real time. Fulfillment logic optimizes for cost, speed, and availability (e.g., intelligent order routing, ship‑from‑store). KPIs and incentives align across functions.
- Level 5: Unified Commerce — Customer, product, inventory, and order data are unified. Policies are consistent, dynamically optimized, and economically managed. Experience, operations, and finance operate as one system, enabling new models (endless aisle, unified subscriptions, marketplace + owned inventory harmonization).
Core dimensions assessed:
- Customer Experience & Journey Design — Consistency of messaging, pricing, and service across touchpoints; continuity of carts/wishlists; cross‑channel returns/exchanges; accessibility and ADA compliance; personalization quality.
- Data, Identity & Analytics — Unified customer ID (CIAM), privacy/consent management, event instrumentation, cross‑channel attribution, experimentation (A/B, holdouts), and actionable insights flowing to frontline decisions.
- Assortment, Pricing & Promotions — Coherence of assortment strategy across channels, price parity/architecture, key value items (KVIs) management, promo governance, and marketplace price hygiene.
- Inventory Visibility & Order Orchestration — Real‑time inventory accuracy, ATP (available‑to‑promise), order management (OMS), intelligent sourcing (DC vs. store vs. vendor drop‑ship), and reverse logistics integration.
- Sales, Service & Fulfillment Operations — Store operations readiness (BOPIS, ship‑from‑store), contact center integration, last‑mile options, SLAs, and cost‑to‑serve management by option.
- Organization, Incentives & Governance — Cross‑channel P&L logic, shared KPIs (e.g., enterprise margin, lifetime value), incentive alignment (crediting rules), decision rights, and transformation governance cadence.
- Technology & Architecture — Modularity and interoperability of commerce, OMS, CRM, CDP, pricing, and content systems; API maturity; data integration; scalability; and security/compliance.
- Measurement & Economics — Attribution quality, promotion incrementality, cost‑to‑serve by journey, inventory productivity (turns, GMROI), price realization, returns economics, and contribution margin at enterprise level.
Practically, teams score each dimension on the maturity scale using evidence (capabilities in production, performance metrics, customer feedback). The output is often a “spider” or heat map highlighting strengths, gaps, and dependencies—an input to a value‑anchored roadmap.
4. When to Use the Omni‑Channel Maturity Model
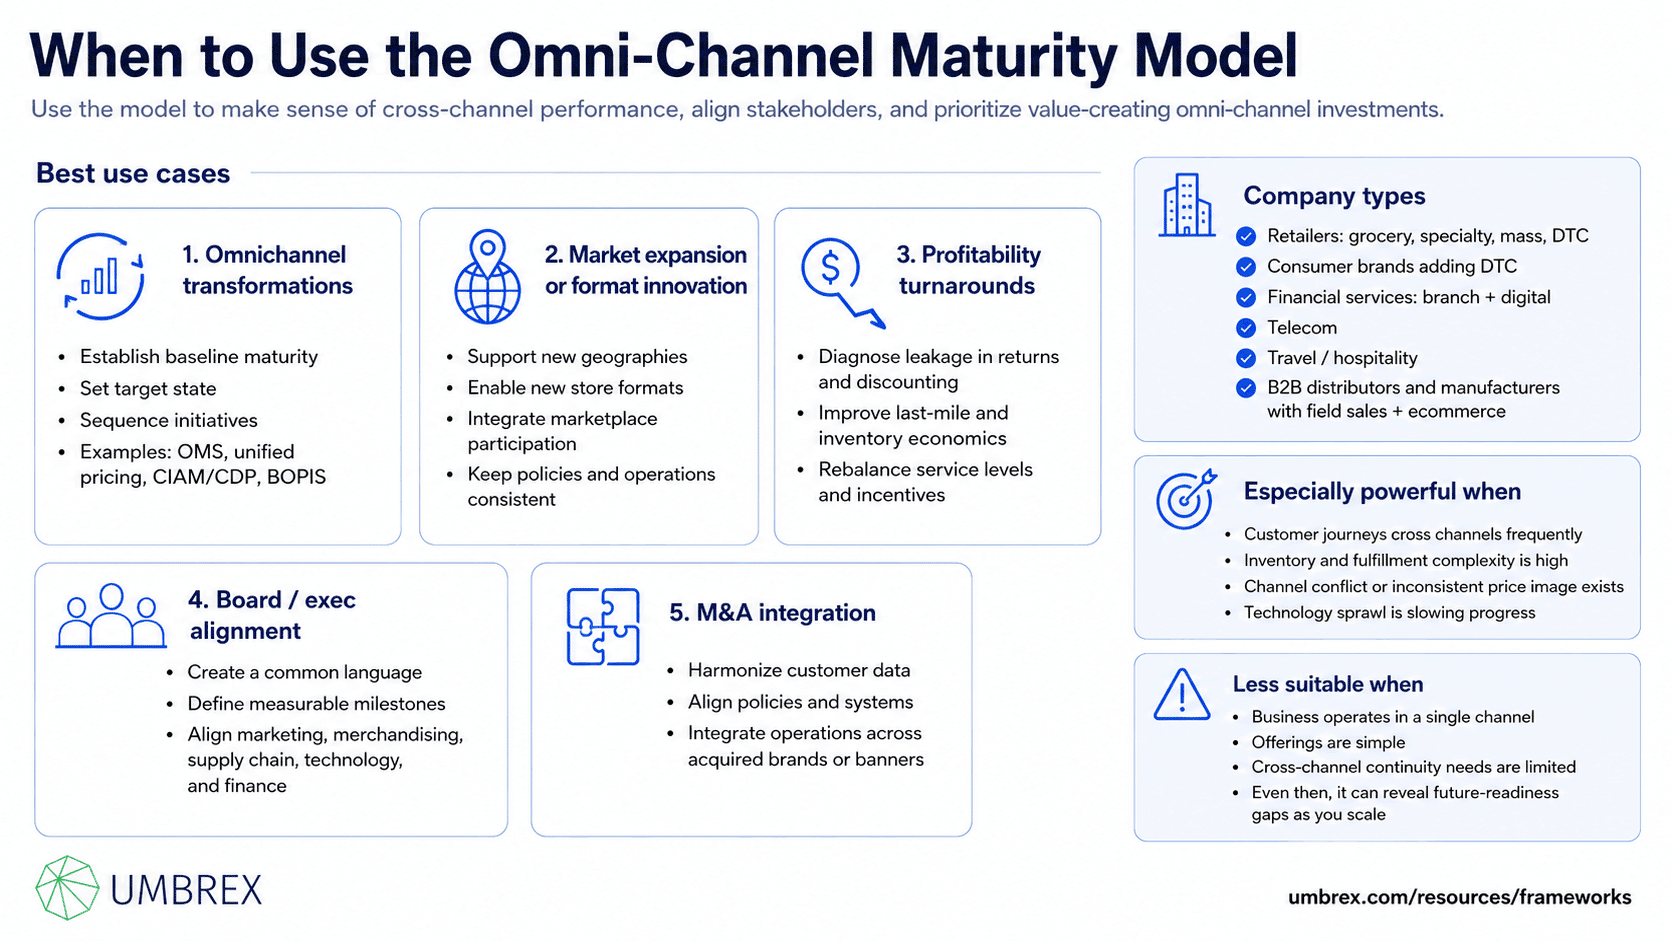
Use the model when you need to make sense of complex, cross‑channel performance and prioritize investments. It is especially helpful for:
- Omnichannel transformations: Establishing a baseline, setting a target state, and sequencing initiatives (e.g., OMS rollout, unified pricing, CIAM/CDP, BOPIS).
- Market expansion or format innovation: Launching new geographies, store formats, or marketplace participation that require consistent policies and integrated operations.
- Profitability turnarounds: Diagnosing leakage from returns, discounting, last‑mile costs, or inventory duplication; rebalancing service levels and incentives.
- Board/exec alignment: Creating a common language and measurable milestones across marketing, merchandising, supply chain, technology, and finance.
- M&A integration: Harmonizing customer data, policies, systems, and operations across acquired brands or banners.
Company types: Retailers (grocery, specialty, mass, DTC), consumer brands adding DTC, financial services with branch + digital, telecom, travel/hospitality, and B2B distributors or manufacturers with field sales plus ecommerce.
Especially powerful when: Customer journeys cross channels frequently; inventory and fulfillment complexity is high; there is channel conflict or inconsistent price image; or technology sprawl is slowing progress.
Less suitable when: You operate in a single channel with simple offerings and limited need for cross‑channel continuity. Even then, the model can flag future readiness gaps as you scale.
5. How to Apply the Omni‑Channel Maturity Model: Step‑by‑Step
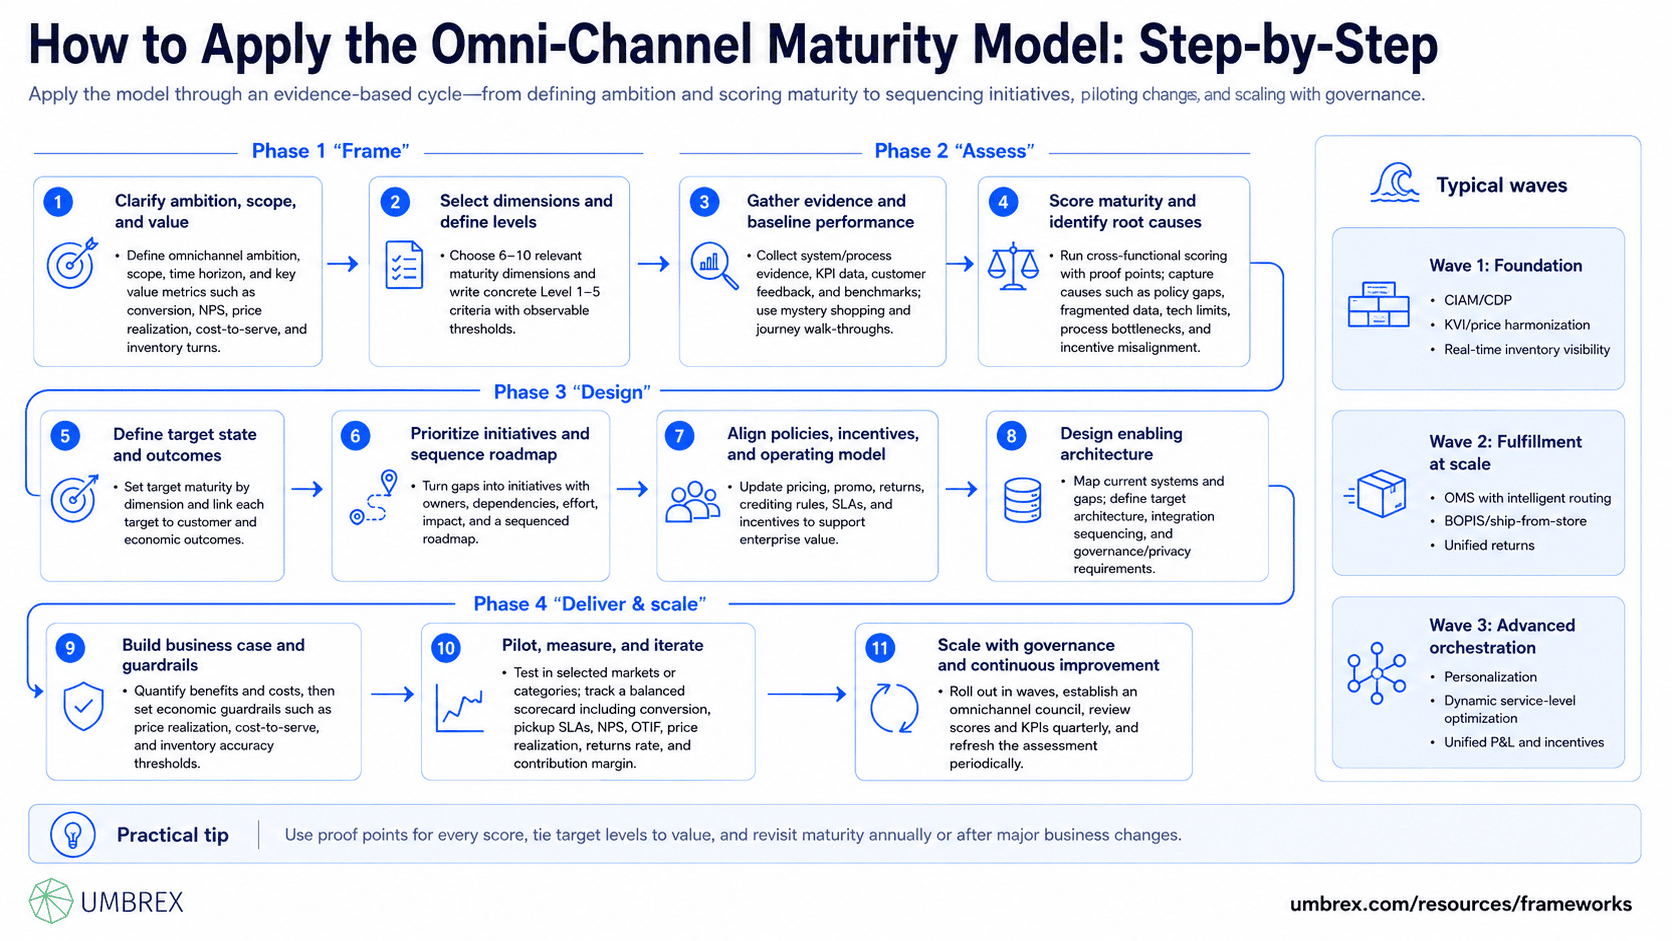
- Clarify ambition, scope, and value.
Define what “omnichannel” means for your business: growth goals, customer outcomes, and financial targets (conversion, NPS, price realization, cost‑to‑serve, inventory turns). Decide scope (brands, geographies, channels) and time horizon (12–24 months for foundation; 36+ for full orchestration).
- Select maturity dimensions and define levels.
Agree on 6–10 dimensions that matter for your context (see above). Document what Level 1–5 look like for each dimension with concrete, observable criteria (e.g., “real‑time inventory accuracy ≥ 97% across stores and DCs,” “cross‑channel returns processed in a single OMS with immediate refund and inventory disposition”). Avoid vague labels.
- Gather evidence and baseline performance.
Collect inputs: system capabilities, process maps, policy documents, KPIs (conversion, AOV, returns rate, OTIF, price realization), customer feedback, and competitive benchmarks. Supplement with mystery shopping and journey walk‑throughs. The goal is an evidence‑based score per dimension—not opinions.
- Score maturity and identify root causes.
Facilitate cross‑functional scoring sessions. Require “proof points” (e.g., logs showing cross‑channel returns volume; OMS routing logic; price audit data). For each low‑scoring area, capture the root causes: policy gaps, data fragmentation, tech limitations, process bottlenecks, or incentive misalignment.
- Define the target state and business outcomes.
Set target levels per dimension tied to value—e.g., Level 4 inventory/order orchestration to enable ship‑from‑store and reduce stock‑outs by X%, improve GMROI by Y%. Articulate customer outcomes (pickup time SLAs, consistent pricing) and economic outcomes (margin lift, returns reduction, CAC efficiency).
- Prioritize initiatives and sequence the roadmap.
Translate gaps into initiatives with owners, dependencies, effort, and impact. Use a simple prioritization lens: value (revenue/margin), feasibility (time, complexity), and dependency (prerequisites). Typical waves:
Wave 1: CIAM/CDP foundation, KVI/price harmonization, real‑time inventory visibility;
Wave 2: OMS with intelligent routing, BOPIS/ship‑from‑store at scale, unified returns;
Wave 3: advanced personalization, dynamic service‑level optimization, unified P&L and incentives. - Align policies, incentives, and operating model.
Rewrite rules of the road: price parity guidance, promo governance, returns/exchanges, crediting rules (who gets credit for BOPIS/ship‑from‑store sales), service SLAs by option. Align incentives to enterprise value (e.g., stores credited for fulfilling online orders).
- Design the enabling architecture.
Map current systems and integration gaps (commerce, OMS, POS, CRM, CDP, PIM, pricing, WMS/TMS). Choose target architecture patterns (API‑first, event‑driven integrations) and integration sequencings. Ensure data governance and privacy are designed in.
- Build the business case and guardrails.
Quantify benefits (conversion lift from BOPIS, sell‑through/markdown reduction from inventory pooling, promo waste reduction from governance) and costs (capex, opex, change). Set economic guardrails: minimum price realization, maximum cost‑to‑serve per fulfillment option, inventory accuracy thresholds.
- Pilot, measure, and iterate.
Run controlled pilots in select markets or categories. Track a balanced scorecard: conversion, pickup SLAs, NPS, OTIF, price realization, returns rate, and contribution margin. Collect frontline feedback. Tune policies and processes before scaling.
- Scale with governance and continuous improvement.
Roll out in waves; establish a quarterly omnichannel council reviewing maturity scores, KPI progress, and backlog reprioritization. Refresh the assessment annually or after major changes (marketplace entry, new format, acquisition).
6. Example: The Omni‑Channel Maturity Model in Action
Company: A $1.1B North American specialty apparel retailer with 450 stores and a growing ecommerce business.
Problem: Online conversion lagged peers, store traffic was volatile, and returns were costly. Pricing and promotions varied by channel, confusing customers. Inventory sat in the wrong places, leading to stock‑outs online and markdowns in stores. The CEO asked for a clear path to “feel unified” to customers and improve margin dollars.
Applying the model: The team assessed eight dimensions. Baseline scores clustered at Level 2–3, with gaps in inventory visibility (Level 2), order orchestration (Level 1–2), pricing/promo governance (Level 2), and incentives (Level 1).
- Root causes: Fragmented identity (no single view of customer), batch inventory updates, channel‑specific promotions, and store KPIs that penalized fulfilling online orders.
- Target state: Level 4 for inventory and OMS (ship‑from‑store, BOPIS within two hours, unified returns), Level 4 for pricing/promo governance (KVI parity, centralized rules), Level 3 for personalization (progressive profiling, basic 1:1 offers).
Initiatives and sequencing:
- Wave 1 (6 months): Implemented CIAM for unified login; harmonized KVIs and promo calendars; introduced real‑time inventory visibility (store and DC). Piloted BOPIS in 60 stores with two‑hour SLA. Adjusted store incentives to credit BOPIS and ship‑from‑store revenue.
- Wave 2 (next 9 months): Rolled out OMS with intelligent order routing; enabled ship‑from‑store in 200 locations; standardized returns policy (cross‑channel refund/exchange); launched basic personalization on site/app tied to loyalty profiles.
- Wave 3 (ongoing): Optimized routing by margin and proximity; refined promo governance to reduce overlapping offers; introduced appointment‑based in‑store styling integrated with online carts.
Results (12 months): Online conversion +80 bps; BOPIS accounted for 18% of digital orders with 92% on‑time pickup; stock‑out rate online reduced by 35%; markdowns down 14% due to ship‑from‑store sell‑through; returns cost per order −12% via unified processing; enterprise contribution margin +220 bps. NPS improved by 7 points as customers cited “seamless pickup and returns.” The maturity assessment moved to Level 3–4 across key dimensions, with a path to Level 4 orchestration in the following year.
7. Strengths and Limitations
Strengths
- Creates a shared language: Aligns marketing, merchandising, supply chain, technology, finance, and stores on what “good” looks like.
- Links capability to outcomes: Connects maturity levels to measurable economics (conversion, price realization, cost‑to‑serve, GMROI) and customer metrics (NPS, repeat rate).
- Prioritizes investment: Clarifies dependencies and sequences work into value‑accretive waves, avoiding “big bang” risk.
- Highlights policy and incentive gaps: Surfaces non‑technology blockers—returns policy, promo governance, crediting rules—that often drive most of the friction.
- Adaptable: Can be tailored by sector (e.g., B2B service SLAs vs. retail last‑mile) and by ambition.
Limitations
- Subjectivity risk: Scoring can drift without clear, evidence‑based criteria and external benchmarks.
- Checklist bias: Teams may “chase levels” rather than outcomes, adding complexity that doesn’t pay back.
- Static snapshots: Without a governance cadence, assessments go stale as customer behavior, competitors, and channels evolve.
- Technology tunnel vision: Overemphasis on systems can miss policy, process, and incentive changes required for value realization.
- One‑size‑fits‑all hazard: The “optimal” level may differ by category, channel, or segment given economics and brand positioning.
8. Common Pitfalls (and How to Avoid Them)
- Equating maturity with value.
What goes wrong: Pursuit of Level 5 everywhere drives cost and complexity without ROI.
How to avoid: Tie target levels to economics and customer outcomes; selectively aim for Level 4–5 where value is proven.
- Scoring on intent, not evidence.
What goes wrong: Roadmaps and pilot pilots are counted as capabilities “in place.”
How to avoid: Require production usage and KPI movement as proof; document artifacts (policies, logs, metrics).
- Technology‑first solutions.
What goes wrong: OMS or CDP deployed without policy/process changes; value fails to materialize.
How to avoid: Pair system changes with policy, incentives, and training; define guardrails (price parity, routing logic, returns rules).
- Ignoring cost‑to‑serve.
What goes wrong: Offering every fulfillment option everywhere erodes margin.
How to avoid: Segment service levels; set option‑level guardrails; optimize by economics and availability.
- Underestimating data and identity foundations.
What goes wrong: Personalization and attribution stall without unified IDs and consent management.
How to avoid: Prioritize CIAM and CDP early; enforce data governance and privacy by design.
- Misaligned incentives.
What goes wrong: Store teams resist fulfilling online orders; channels compete rather than collaborate.
How to avoid: Redesign crediting and KPIs to reward enterprise value; communicate “one P&L” logic.
- One‑and‑done assessments.
What goes wrong: Momentum fades; priorities drift as new fires emerge.
How to avoid: Establish quarterly governance; refresh scores and roadmap based on KPI progress and tests.
9. How the Omni‑Channel Maturity Model Relates to Other Frameworks
- Route‑to‑Market (RTM) Design: RTM decides which channels and partners participate and their roles. The maturity model assesses how well those channels are integrated in experience, data, operations, and economics.
- Segmentation–Targeting–Positioning (STP): STP defines who you serve and the value proposition. The maturity model ensures you can deliver that proposition consistently across journeys and channels.
- Customer Journey Mapping: Journey maps reveal friction points. The maturity model translates them into capability gaps and a prioritized roadmap to fix the root causes.
- Category Management & Category Role Framework: Category roles guide pricing, assortment, and promotions by category. Omni‑channel maturity ensures those choices are executed coherently across digital and physical channels.
- Pricing Architecture & Discount Governance: These set rules for price and promo. The maturity model tests cross‑channel consistency and enforcement via systems and incentives.
- Target Operating Model (TOM) / 7‑S: TOM aligns structure, processes, and systems. The maturity model provides the diagnostic baseline and target levels to inform TOM design.
- Attribution & MMM / Experimentation: Analytics frameworks measure impact. Maturity depends on having robust attribution and testing to guide omnichannel decisions.
- PESTLE & Scenario Planning: External trends (privacy regulation, logistics constraints, marketplace dynamics) can raise or lower the bar for certain dimensions; feed scenario insights into target levels and roadmap.
Choosing among tools: If the question is “Which channels should we use and how should they work together?” start with RTM. If it’s “How do we deliver a seamless experience and coherent economics across those channels?” use the Omni‑Channel Maturity Model. Use journey mapping to find friction and pricing/assortment frameworks to define policies; feed their outputs into the maturity roadmap.
10. Key Takeaways
- The Omni‑Channel Maturity Model assesses how well you integrate experience, data, operations, and technology across channels, from siloed to unified commerce.
- Evaluate maturity across clear, evidence‑based dimensions (experience, data/identity, pricing/promo, inventory/OMS, fulfillment, org/incentives, tech, measurement).
- Use it to prioritize a value‑anchored roadmap—sequencing foundations (identity, inventory visibility) before advanced orchestration.
- Align policies and incentives to enterprise outcomes; technology alone won’t deliver omnichannel value.
- Don’t chase the highest level everywhere; target maturity by economics and customer impact, and refresh the assessment regularly.
11. FAQs About the Omni‑Channel Maturity Model
Is the Omni‑Channel Maturity Model still relevant today?
Yes. As marketplaces, social commerce, and new fulfillment models expand, the need for integrated experience and economics has increased. What’s evolved is the emphasis on identity, data governance, and economically optimized service levels—not just feature checklists.
How many levels and dimensions should we use?
Five levels are common and intuitive. Choose 6–10 dimensions that reflect your business (e.g., B2B may emphasize service SLAs and partner integration; retail emphasizes OMS and last‑mile). Define observable criteria for each level to reduce subjectivity.
Does higher maturity always mean better results?
Not necessarily. The “right” maturity level varies by category, segment, and brand position. Aim where the economics justify it—e.g., Level 4 OMS for fast‑moving categories with high stock‑out costs; Level 3 may suffice elsewhere.
How long does an assessment take?
A robust baseline typically takes 3–6 weeks, including data gathering, cross‑functional workshops, and customer/competitor scans. Building and launching the first wave of initiatives usually spans 3–9 months, depending on scope and system changes.
Can B2B companies use this model?
Absolutely. Replace consumer touchpoints with account journeys (field sales, portals, distributors, service). Emphasize identity across buying centers, contract pricing consistency, availability/lead times, and post‑sale service integration.
How should we benchmark against peers?
Use external price/promo audits, mystery shopping, feature parity scans, and operational benchmarks (pickup SLAs, returns rates, inventory accuracy). Triangulate with customer feedback and financial metrics (price realization, GMROI, cost‑to‑serve) to avoid vanity comparisons.
