

1. What Is the Direct vs Indirect Channel Matrix?
The Direct vs Indirect Channel Matrix is a decision framework for selecting and managing routes to market. It helps leaders compare direct channels (where you acquire, sell to, fulfill, and support the customer yourself) versus indirect channels (where intermediaries—distributors, resellers, marketplaces, agents, OEMs—play some or all of those roles). By plotting channel options along clear dimensions—control, reach, economics, data access, capability requirements—you can design a channel mix that maximizes profitable growth and protects brand equity.
It is a pricing, channel, and sales framework. It ties strategy (who we serve, with what offer) to execution (who owns demand generation, the commercial relationship, fulfillment, and service) and to economics (list prices, wholesale discounts, trade spend, pocket price after the price waterfall). The matrix simplifies complex choices into a structured conversation: where to go direct, where to go via partners, where to blend, and under what rules.
Consultants and executives use this framework frequently because it aligns Product, Sales, Marketing, Channel, and Finance on the same facts: the trade-offs between speed and control; gross margin and pocket price; data ownership and partner leverage; scalability and enablement cost. It is especially valuable during launches, scale-up, geographic expansion, and when channel conflict threatens margins or brand.
2. Origin and Background
Origin: Unknown; in use since at least the 1990s.
The matrix builds on classic go-to-market and route-to-market design in B2B and B2C: direct sales vs. reseller/distributor models, retail vs. D2C, and more recently, marketplaces. As digital channels proliferated and retail consolidated, firms needed a practical tool to compare channel archetypes on economics and control. The matrix became common through business school teaching, consulting practice, and its codification in channel strategy playbooks.
It was created to solve a recurring problem: teams debated channel choices based on anecdotes (“partners are slow,” “DTC is expensive”) rather than data. The matrix provides a systematic way to evaluate options, set guardrails (e.g., MAP, price parity), and run controlled pilots before scaling.
3. How the Direct vs Indirect Channel Matrix Works
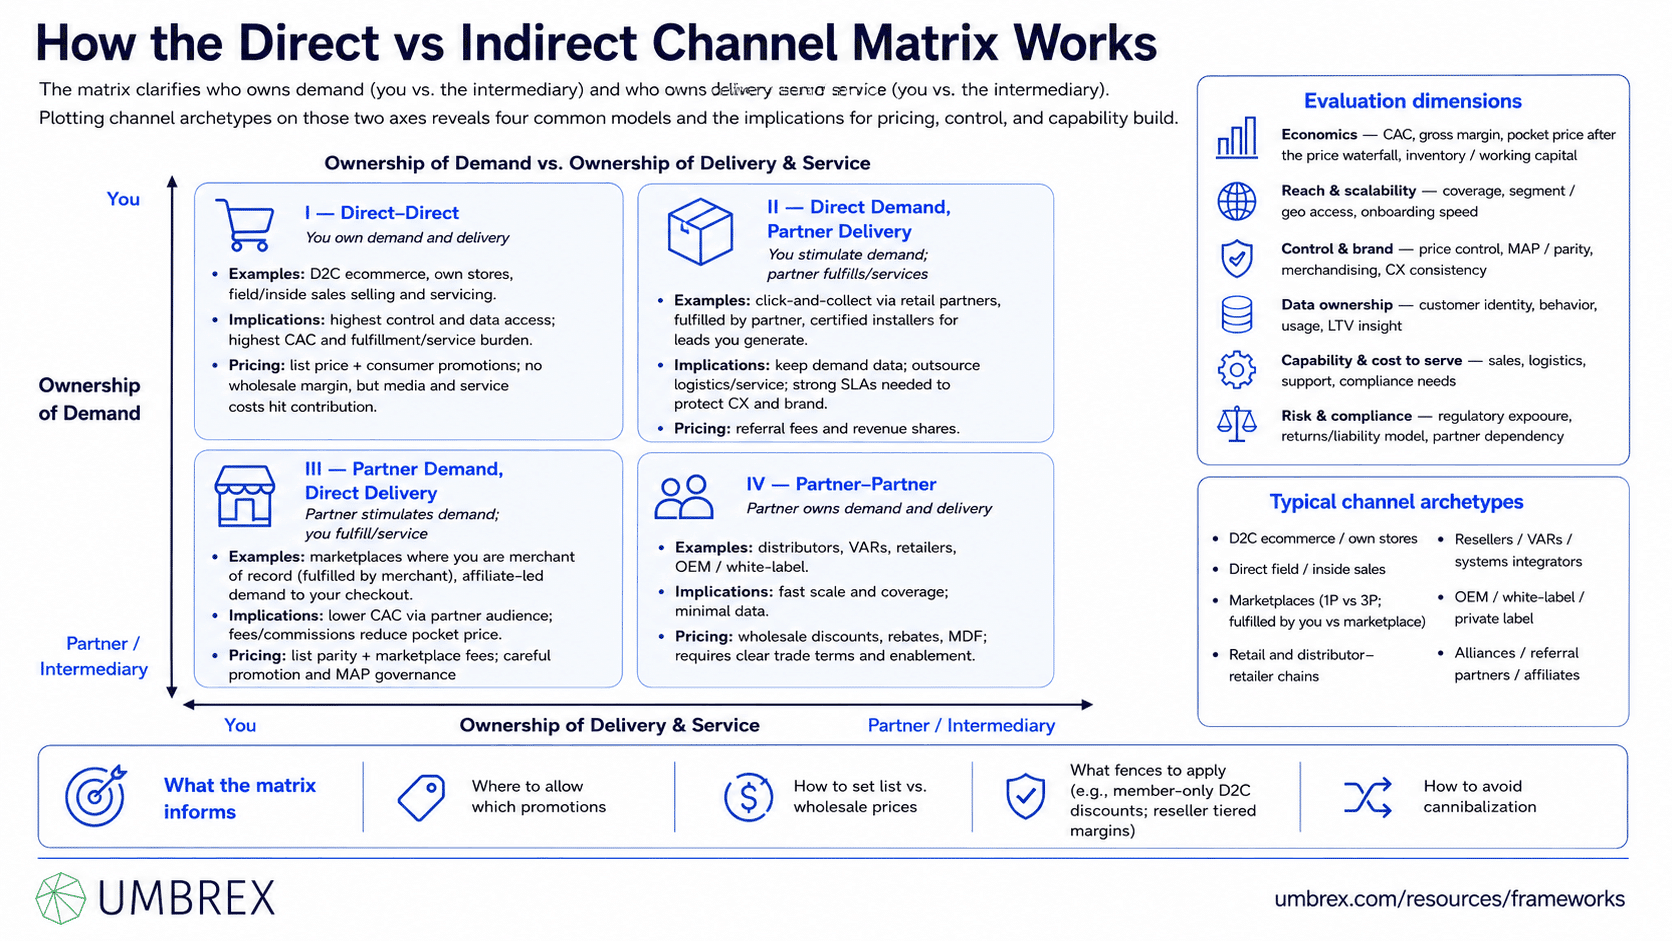
At its core, the matrix clarifies who owns demand (you vs. the intermediary) and who owns delivery and service (you vs. the intermediary). Plotting channel archetypes on these two axes reveals four common models and the implications for pricing, control, and capability build.
The 2×2: Ownership of Demand vs Ownership of Delivery
- Quadrant I — Direct–Direct (You own demand and delivery):
Examples: D2C ecommerce, your own stores, your field/inside sales selling and servicing.
Implications: Highest control and data access; highest CAC and fulfillment/service burden. Pricing: list price with consumer promotions; no wholesale margin but performance media and service costs hit contribution.
- Quadrant II — Direct Demand, Partner Delivery (You stimulate demand; partner fulfills/services):
Examples: Click-and-collect via retail partners, “Fulfilled by Partner,” certified installers for leads you generate.
Implications: Keep demand data; outsource logistics/service. Pricing: referral fees, revenue shares; need strong SLAs to protect CX and brand.
- Quadrant III — Partner Demand, Direct Delivery (Partner stimulates demand; you fulfill/service):
Examples: Marketplaces where you are the merchant of record (fulfilled by merchant), affiliate-led demand to your checkout.
Implications: Lower CAC via partner audience; fees/commissions reduce pocket price. Pricing: list parity plus marketplace fees; careful promotion and MAP governance.
- Quadrant IV — Partner–Partner (Partner owns demand and delivery):
Examples: Distributors, VARs, retailers, OEM/white-label.
Implications: Fast scale and coverage; minimal data; pricing through wholesale discounts, rebates, MDF. Requires clear trade terms and enablement.
Evaluation Dimensions
For each archetype, assess:
- Economics: CAC by channel; gross margin vs. pocket price after the price waterfall (discounts, rebates, commissions, freight, returns); inventory and working capital implications.
- Reach and scalability: Addressable coverage, access to priority segments/geos, speed of onboarding.
- Control and brand: Ability to set price, enforce MAP/parity, control merchandising, deliver consistent CX.
- Data and relationship ownership: Access to customer data (identity, behavior, usage) for LTV and product roadmap.
- Capability and cost to serve: Sales coverage, logistics, service/support, compliance requirements.
- Risk and compliance: Regulatory exposure, returns/liability model, partner dependency/concentration risk.
Typical Channel Archetypes to Place on the Matrix
- D2C ecommerce, your stores/showrooms
- Direct field/inside sales
- Marketplaces (1P vs 3P; fulfilled by you vs fulfilled by marketplace)
- Retail (national, specialty); distributor–retailer chains
- Resellers/VARs/Systems integrators; agents/brokers
- OEM/white-label/private label
- Alliances/referral partners/affiliates
The matrix is not just static positioning; it informs rules: where to allow which promotions, how to set list vs wholesale prices, what fences to apply (e.g., member-only D2C discounts; reseller tiered margins), and how to avoid cannibalization.
4. When to Use the Direct vs Indirect Channel Matrix
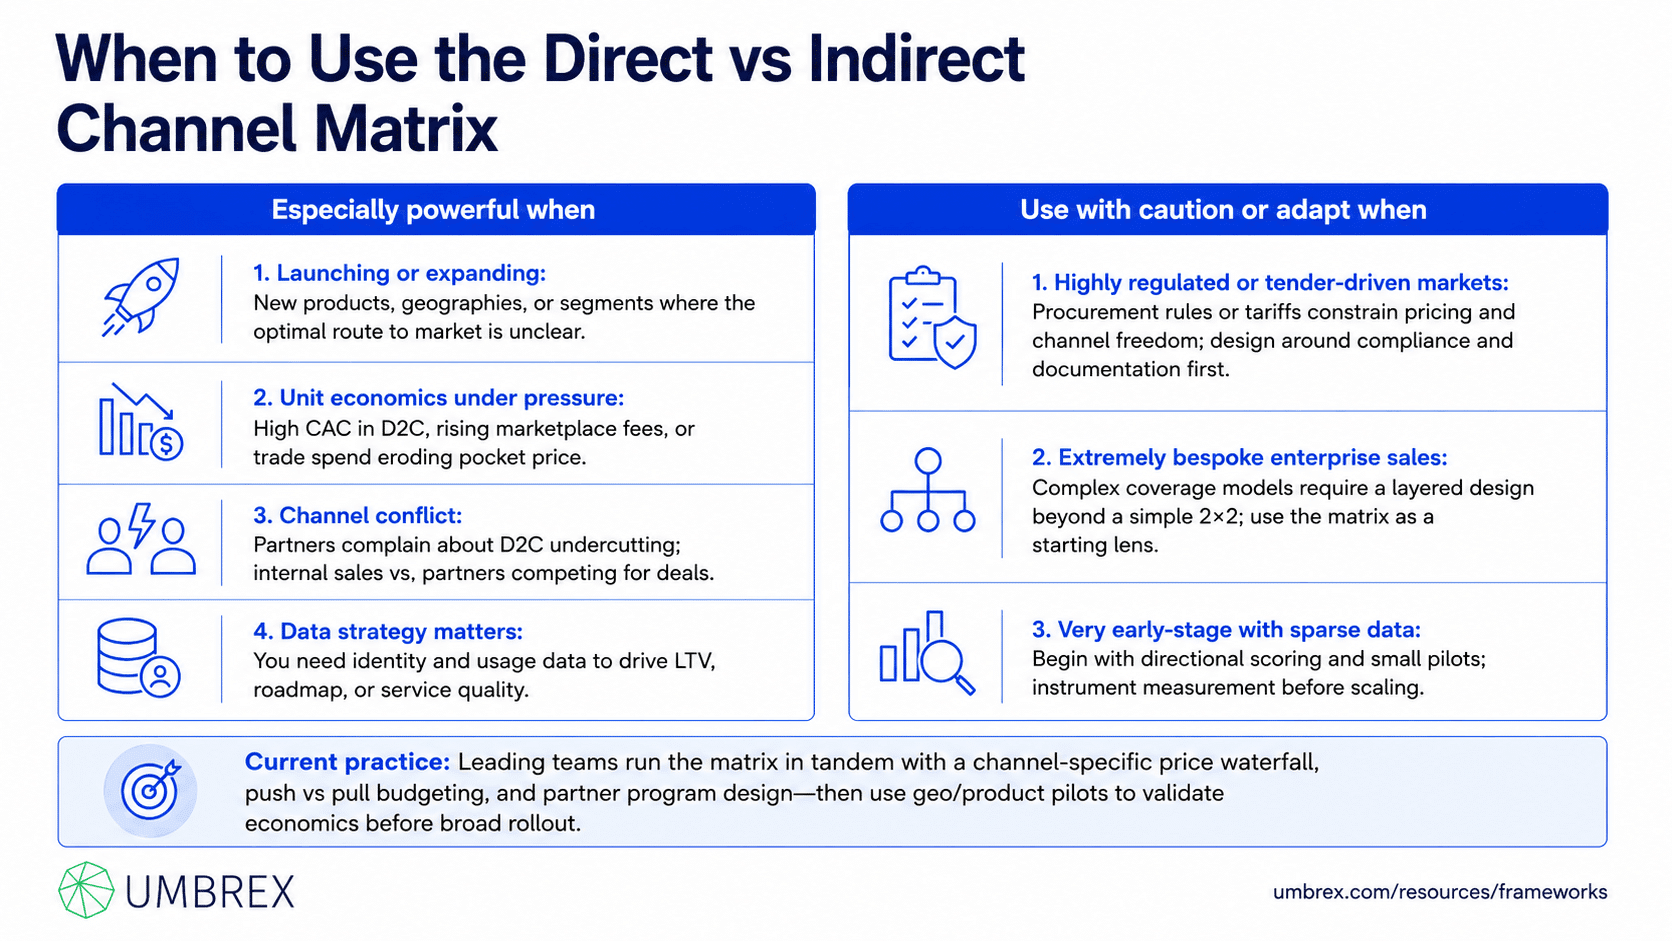
Especially powerful when:
- Launching or expanding: New products, geographies, or segments where the optimal route to market is unclear.
- Unit economics under pressure: High CAC in D2C, rising marketplace fees, or trade spend eroding pocket price.
- Channel conflict: Partners complain about D2C undercutting; internal sales vs. partners competing for deals.
- Data strategy matters: You need identity and usage data to drive LTV, roadmap, or service quality.
Use with caution or adapt when:
- Highly regulated or tender-driven markets: Procurement rules or tariffs constrain pricing and channel freedom; design around compliance and documentation first.
- Extremely bespoke enterprise sales: Complex coverage models (global account management, integrators) require a layered design beyond a simple 2×2; use the matrix as a starting lens.
- Very early-stage with sparse data: Begin with directional scoring and small pilots; instrument measurement before scaling.
Current practice: Leading teams run the matrix in tandem with a channel-specific price waterfall, push vs pull budgeting, and partner program design—then use geo/product pilots to validate economics before broad rollout.
5. How to Apply the Direct vs Indirect Channel Matrix: Step-by-Step
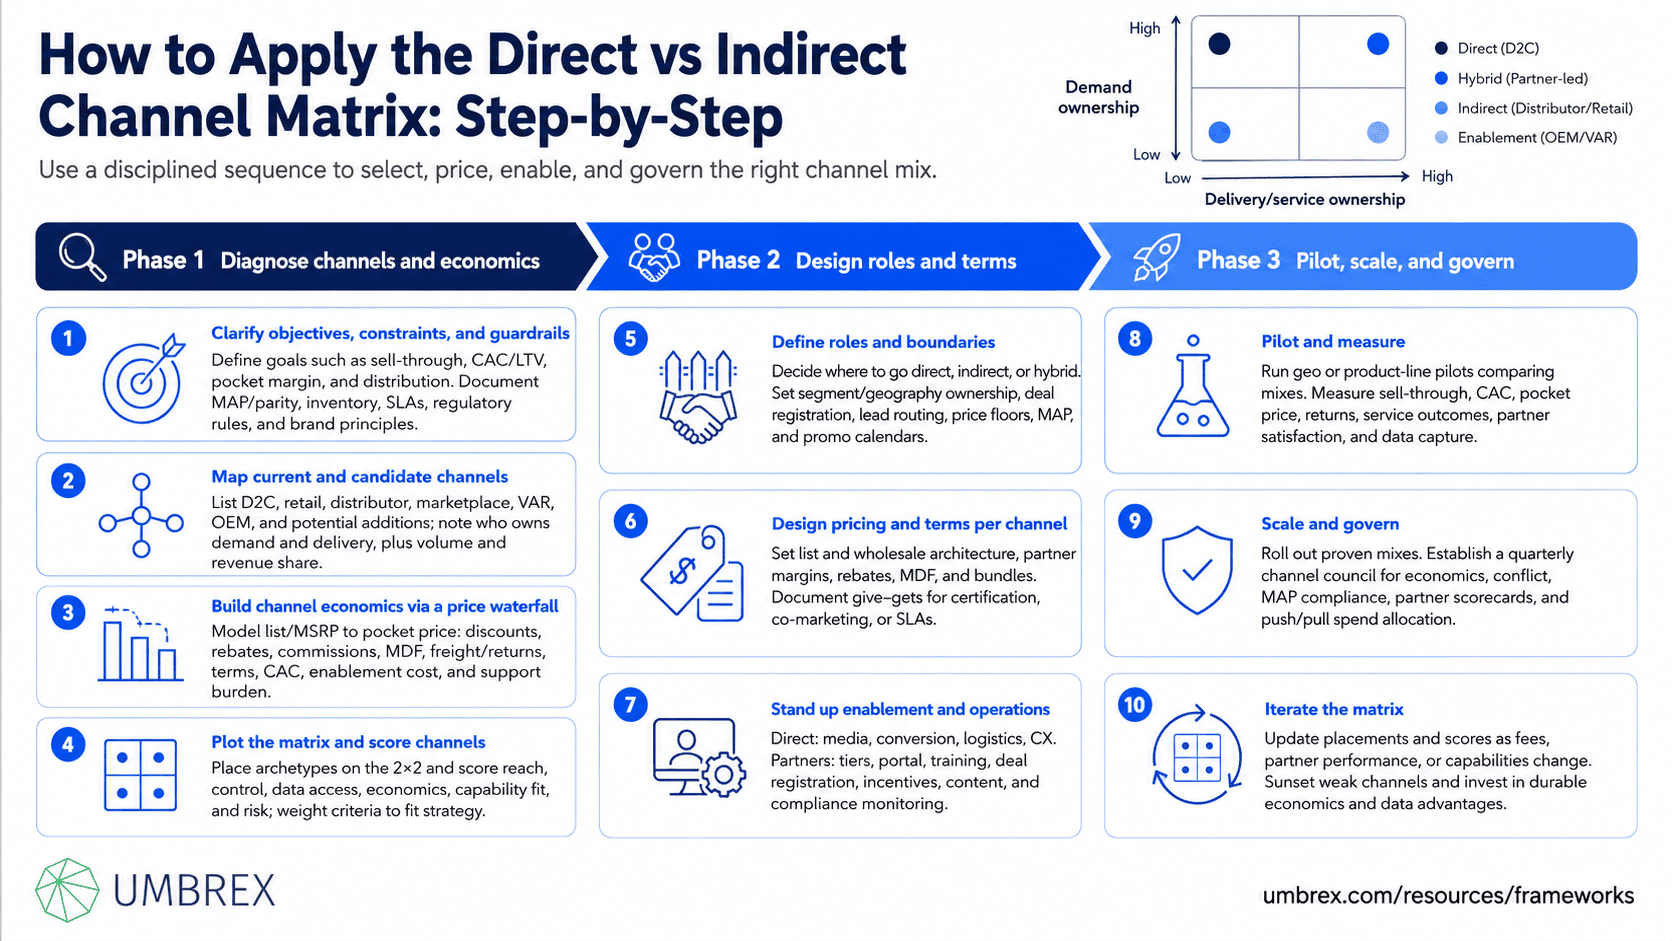
- Clarify objectives, constraints, and guardrails
Define goals (e.g., +20% sell-through, CAC/LTV ≥3.0, pocket margin +200 bps, 80% national distribution). Document constraints: MAP/parity policies, inventory capacity, service SLAs, regulatory rules, and brand principles.
- Map current and candidate channels
List existing routes (D2C, retail, distributor, marketplace, VAR, OEM) and potential additions. For each, note who owns demand, who owns delivery, and your current share of volume and revenue.
- Build channel economics via a price waterfall
For each route, model list/MSRP to pocket price: on-invoice discounts, off-invoice rebates, commissions/fees, MDF/co-op, freight/returns, payment terms. Add CAC, onboarding/enablement cost, and support burden to estimate contribution per order/customer.
- Plot the matrix and score channels
Place each archetype on the 2×2 (demand ownership vs delivery ownership). Score channels (e.g., 1–5) on reach, control, data access, economics, capability fit, and risk. Weight criteria to reflect strategy (e.g., data may outweigh near-term margin).
- Define roles and boundaries
Decide where to go direct, indirect, or hybrid. Set clear rules: segment/geography ownership, deal registration, lead routing, price floors/MAP, and promotional calendars. Use price fences (e.g., member-only D2C offers; reseller tier discounts) to reduce leakage.
- Design pricing and terms per channel
Set list and wholesale price architectures, tiered partner margins, rebates, MDF, and service bundles. Document give–gets (e.g., higher margin for certification, co-marketing, or SLA targets). Ensure parity policies are enforceable and lawful.
- Stand up enablement and operations
For direct routes: invest in performance media, conversion, logistics, CX. For partners: build a partner program (tiers, portal, training, deal reg, incentives), content (battlecards, demos), and compliance monitoring.
- Pilot and measure
Run geo or product-line pilots comparing mixes (e.g., marketplace-heavy vs D2C-heavy vs reseller-led). Measure sell-through, CAC, pocket price, returns, service outcomes, partner satisfaction, and data capture. Use holdouts where possible to isolate incremental impact.
- Scale and govern
Roll out proven mixes. Establish a quarterly channel council to review economics, conflict cases, MAP compliance, partner scorecards, and reallocate spend across push (trade/MDF) and pull (media) with guardrails.
- Iterate the matrix
Update placements and scores as fees, partner performance, or your capability set changes. Sunset underperforming channels; invest in those showing durable unit economics and data advantages.
6. Example: The Matrix in Action
Company: “VoltEdge,” a $250M industrial IoT firm selling wireless sensors and monitoring software to manufacturing plants.
Problem: Growth stalled in mid-market. Direct enterprise sales were strong but expensive (CAC high, long cycles). Regional distributors had reach but inconsistent messaging and discounted aggressively. Marketplaces were emerging for MRO (maintenance, repair, operations) buyers, but internal teams feared channel conflict and price erosion.
Application:
- Channel mapping: Plotted D2C (inbound + inside sales), regional distributors (stock and service), VARs (integration projects), and a major industrial marketplace (partner demand, direct delivery) on the 2×2. Added a certified installer network concept (direct demand, partner delivery).
- Economics (waterfalls): D2C had highest list price realization but high CAC and support costs; distributors carried 25–35% margin plus MDF; marketplace took 12–15% fees and imposed strict return policies; VARs demanded 20–30% margin but drove bundled projects with higher average deal size.
- Insights: Mid-market buyers researched online (pull) but preferred local installation and support. Distributor discounting depressed pocket price; marketplace buyers accepted list parity if logistics were reliable and content/ratings strong.
- Design:
- Keep enterprise direct with field sales; add installer certification to offload onsite service.
- Launch marketplace for core SKUs (partner demand, direct delivery) with strict MAP and premium content; use fulfillment SLAs to protect ratings.
- Resegment distributors: move from blanket margin to tiered margins and rebates tied to sell-through, certification, and price compliance; introduce deal registration to prevent gray-market leakage.
- D2C: invest in performance media and technical content to capture research-stage demand; route “install required” leads to certified partners with referral fees.
- Pilots: Three regions ran different mixes. The “balanced” region (marketplace + D2C content + certified installers; re-tiered distributors) outperformed on pocket price and growth.
Results (16 weeks): Mid-market bookings +22%, pocket price +180 bps overall (distributor leakage cut in half), CAC −15% as marketplace audience supplemented inbound. Installer attach rate reached 47% of D2C leads, cutting time-to-live by 10 days and reducing support tickets. Partner NPS improved after program clarity; MAP violations dropped 60% with monitoring and enforceable penalties.
Follow-on: VoltEdge scaled the balanced model nationally, added a partner portal, and instituted a quarterly channel council to adjust rebates, MDF, and marketplace mix using updated waterfalls and performance data.
7. Strengths and Limitations
Strengths
- Clarity on trade-offs: Visualizes where you gain control and data versus where you gain reach and speed.
- Economic rigor: Forces channel-by-channel pocket price and CAC analysis via the price waterfall.
- Conflict reduction: Establishes role clarity and guardrails (MAP, deal reg, lead routing) to reduce internal and partner friction.
- Scalability: Guides phased pilots and investments rather than “all-in” bets.
Limitations
- Not a one-number answer: The matrix frames choices; it doesn’t replace market tests and partner due diligence.
- Snapshot bias: Fees, partner policies, and your capabilities evolve; placements and scores must be refreshed.
- Complex realities: Large enterprises need layered coverage (global accounts + local partners) that exceed a simple 2×2; use it as a foundation, not the full design.
- Attribution challenges: Omnichannel spillovers complicate CAC and ROI measurement; plan for geo/holdout testing and shared KPIs.
8. Common Pitfalls (and How to Avoid Them)
- Ignoring the price waterfall
What goes wrong: Overestimation of margin in indirect routes; hidden fees and trade spend collapse pocket price.
How to avoid: Build a full channel waterfall (discounts, rebates, commissions, freight, returns, terms) and set pocket price floors. - Channel conflict from unmanaged parity
What goes wrong: D2C promos undercut partners; partners retaliate with discounts.
How to avoid: Set and enforce MAP/parity; use fenced D2C offers (member-only, bundles) and partner-only bundles instead of raw price cuts. - Underinvesting in enablement
What goes wrong: Partners miss targets due to poor training, content, or support; blame the model.
How to avoid: Fund a partner program (tiers, certifications, deal reg, MDF tied to outcomes) and a content factory. - “Set and forget” channel mix
What goes wrong: Marketplace fees rise; distributor power shifts; you don’t react.
How to avoid: Quarterly channel council; re-score the matrix; reallocate spend based on updated economics. - Data blindness
What goes wrong: Indirect routes cut you off from customer identity and usage.
How to avoid: Negotiate data-sharing clauses; add first-party capture (registrations, warranty, loyalty) and value exchanges for customers to share data post-sale. - Double-paying for the same demand
What goes wrong: Paying both retail media (push) and consumer discounts (pull) for the same conversion.
How to avoid: Integrate push vs pull planning; use holdouts; attribute incrementality before layering spend. - Misaligned incentives
What goes wrong: Sales comp and partner incentives drive sell-in, not sell-through;
How to avoid: Tie compensation and rebates to sell-through, pocket price, and compliance, not just bookings.
9. How the Matrix Relates to Other Frameworks
- Price Waterfall: Essential companion to quantify pocket price by channel and set floors and guardrails.
- Push vs Pull Strategy: Determines whether to invest in channel-facing spend (push) or end-customer demand (pull) for each route; align with your matrix choices.
- Price Fences Framework: Use fences to segment offers (member-only D2C, reseller tiers) and minimize leakage across routes.
- Good–Better–Best (GBB): Align tiered packaging to channels (e.g., “Good” via retail, “Better/Best” via partners or direct) while protecting fences and price gaps.
- Promotional Mechanics: Select channel-appropriate mechanics (MDF, rebates, retail media vs consumer coupons and bundles) within economic guardrails.
- Revenue Management (Price, Capacity, Yield): In constrained environments, coordinate channel availability and price to optimize yield by date/segment.
Choosing the stack: Use the matrix to decide route-to-market; the price waterfall to secure economics; push/pull to allocate spend; price fences and GBB to package and protect offers; and governance (MAP, deal reg) to sustain discipline.
10. Key Takeaways
- The Direct vs Indirect Channel Matrix plots who owns demand and who owns delivery to clarify control, reach, economics, and data trade-offs.
- Evaluate each route with a price waterfall, CAC, data access, and capability fit—then set channel-specific pricing, terms, and guardrails.
- Use pilots and matched-market tests to validate the mix before scaling; govern with MAP, deal registration, partner tiers, and a channel council.
- Expect the answer to be hybrid: design roles and boundaries to reduce conflict and protect pocket price and brand.
- Refresh the matrix quarterly as marketplace fees, partner power, and your capabilities evolve.
11. FAQs About the Direct vs Indirect Channel Matrix
Is going direct always better because of higher margins?
Not necessarily. Direct routes avoid wholesale margins but carry higher CAC, fulfillment, and service costs—and require capabilities many firms lack. The right answer depends on pocket price after the waterfall, LTV, and data value, not list margins alone.
How do we avoid channel conflict when adding D2C to a partner-led business?
Set clear roles (segments, SKUs, or geos), enforce MAP/parity, use fenced D2C offers (bundles, loyalty), and implement deal registration and lead routing with partners. Tie partner incentives to sell-through and compliance, not just sell-in.
Are marketplaces worth the fees?
Often, yes—for incremental reach and lower CAC. But fees and return policies can erode pocket price. Model the full waterfall, target SKUs with fit (standardized, shippable), invest in content/ratings, and set strict parity/price controls.
How long does it take to stand up an indirect program?
A focused pilot with 5–10 partners can stand up in 8–12 weeks (tiers, margins, MDF, deal reg, enablement). Scaling nationally or globally typically takes 2–3 quarters with systems (PRM/partner portals) and legal updates.
Can small or early-stage companies use this framework?
Yes. Start with a lightweight matrix and simple waterfalls for 2–3 routes (e.g., D2C + one marketplace + 2 resellers). Run small pilots with clear KPIs and guardrails; invest where unit economics and data access are strongest.
What metrics should we monitor ongoing?
By channel: CAC, pocket price vs list, sell-through, inventory turns, return rate, compliance (MAP, parity), data capture (opt-in rates), partner scorecard (pipeline, certification), and contribution margin. Review monthly; reallocate quarterly.
