

1. What Is the Customer Lifetime Value (CLV / LTV) Model?
The Customer Lifetime Value (CLV, also called LTV) Model estimates the total economic value a customer (or account) will generate for your business over the relationship, net of the costs to serve them. In plain terms: CLV answers “What is this customer worth—profitably—over time?”
As a measurement, analytics, and performance management framework, CLV connects marketing, product, pricing, and channel decisions to cash and profit. It turns retention, purchase frequency, order value, price realization, and cost-to-serve into a single number (or distribution) you can use to set customer acquisition cost (CAC) guardrails, prioritize segments and channels, design promotions and price fences, and measure the impact of onboarding and product improvements. Properly built, CLV is contribution-based (not revenue-only) and sensitive to route-to-market economics (e.g., marketplace fees, retail media, returns).
Executives and consultants use CLV to steer growth investments toward customers and cohorts that generate superior unit economics, to manage CAC/LTV ratios credibly, and to forecast cash flows and enterprise value with fewer surprises.
2. Origin and Background
Origin: Unknown; in use since at least the 1980s in direct marketing and financial services, and popularized in the 1990s–2000s through CRM and subscription businesses.
Why it was created: Period metrics (e.g., last month’s revenue) obscure whether growth is profitable and sustainable. CLV emerged to value a customer as an asset by integrating future retention, monetization, and cost-to-serve, enabling rational acquisition and retention decisions.
How it became known: Through direct/database marketing practice, academic work on customer equity, and later SaaS/ecommerce analytics. Modern CLV models incorporate digital telemetry, cohort analysis, and price realization (via the price waterfall) to reflect true economics.
3. How the CLV Model Works
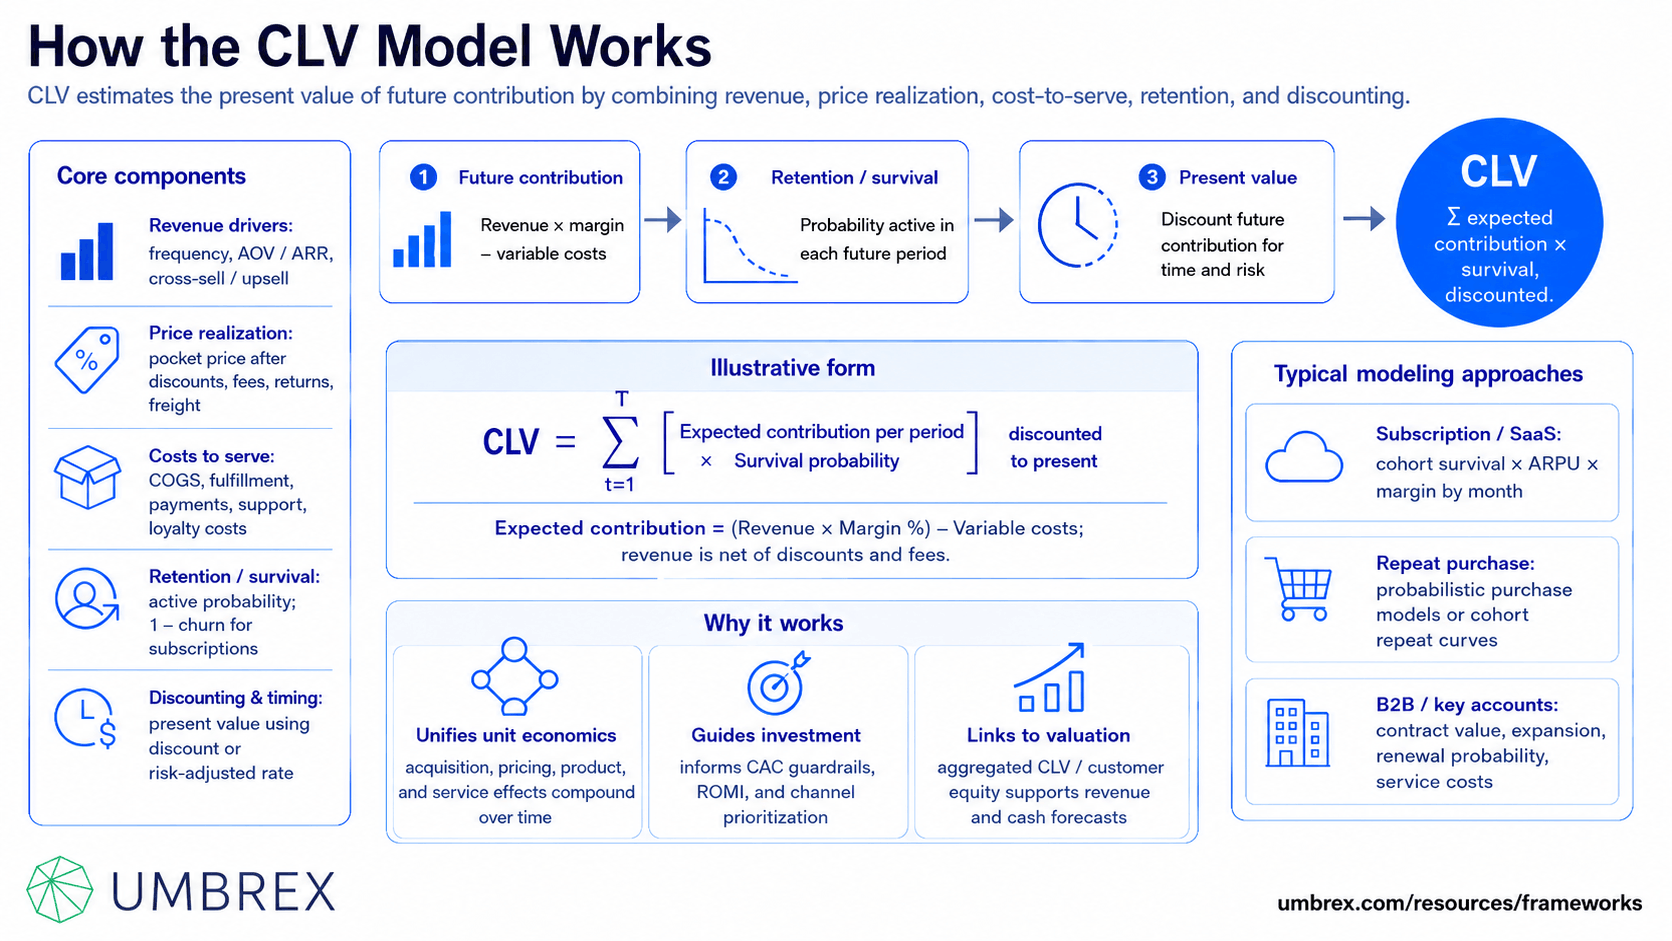
CLV estimates the present value of future contribution (gross margin minus variable costs) from a customer, less the costs needed to acquire and serve them. The logic is consistent across businesses; the implementation varies (subscription vs repeat purchase; B2C vs B2B).
Core Components
- Revenue drivers: Purchase frequency, average order value (AOV) or annual recurring revenue (ARR), cross-sell/upsell.
- Price realization: Pocket price after discounts, rebates, channel fees, returns, freight, and payment terms (the price waterfall).
- Costs to serve: Cost of goods, fulfillment, payment processing, returns, support, and (if modeled at CLV level) retention/loyalty costs.
- Retention/survival: Probability the customer remains active and generates contribution in each future period; for subscriptions, 1 − churn rate.
- Discounting and timing: Present value of future contribution, using an appropriate discount rate or risk-adjusted approach.
Typical Modeling Approaches
- Subscription/SaaS: Use cohort-based survival and ARPU (average revenue per user) × margin by month; CLV is the discounted sum of expected margin streams over the expected tenure.
- Non-subscription/repeat purchase: Use probabilistic purchase models (e.g., BG/NBD–Pareto) or simple cohort curves of repeat rates and spend; multiply by contribution per order and adjust for returns/fees.
- B2B/key accounts: Account-level CLV combines contract value, expansion (seats/modules), renewal probabilities, and service costs; often scenario-based with executive review.
Illustrative Form (conceptual)
CLV = Σ over periods [Expected Contribution per period × Survival probability] discounted to present
Where Expected Contribution per period = (Revenue × Margin %) − Variable Costs, and Revenue is net of discounts and fees (pocket price). The discounting reflects time value and risk; survival probability reflects retention/churn.
Why It Works
- Unifies unit economics: One metric captures how acquisition, pricing/promo, product, and service decisions compounding over time affect value.
- Guides investment: CLV underpins CAC guardrails, ROMI, and channel prioritization, with realism about price realization and fees.
- Links to valuation: Aggregated CLV (customer equity) informs revenue and cash forecasts, especially in subscription and high-repeat models.
4. When to Use the CLV Model
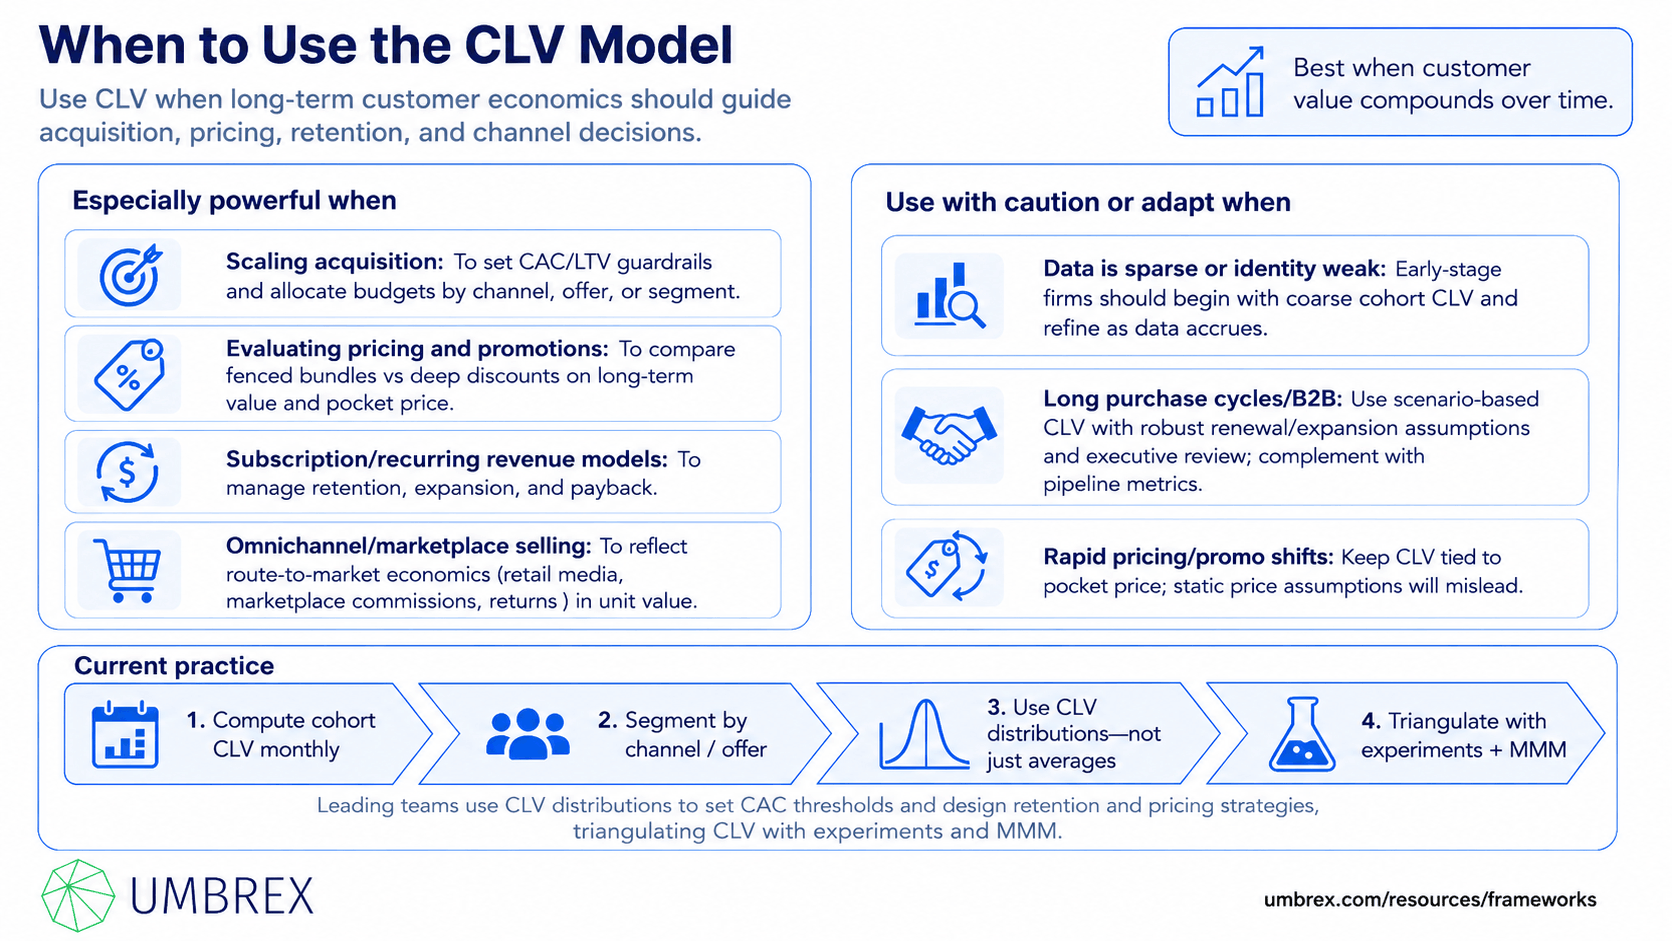
Especially powerful when:
- Scaling acquisition: To set CAC/LTV guardrails and allocate budgets by channel, offer, or segment.
- Evaluating pricing and promotions: To compare fenced bundles vs deep discounts on long-term value and pocket price.
- Subscription/recurring revenue models: To manage retention, expansion, and payback.
- Omnichannel/marketplace selling: To reflect route-to-market economics (retail media, marketplace commissions, returns) in unit value.
Use with caution or adapt when:
- Data is sparse or identity weak: Early-stage firms should begin with coarse cohort CLV and refine as data accrues.
- Long purchase cycles/B2B: Use scenario-based CLV with robust renewal/expansion assumptions and executive review; complement with pipeline metrics.
- Rapid pricing/promo shifts: Keep CLV tied to pocket price; static price assumptions will mislead.
Current practice: Leading teams compute cohort CLV monthly, segment by channel/offer, and use CLV distributions—not just averages—to set CAC thresholds and design retention and pricing strategies. They triangulate CLV with experiments (causality) and MMM (portfolio allocation).
5. How to Apply the CLV Model: Step-by-Step
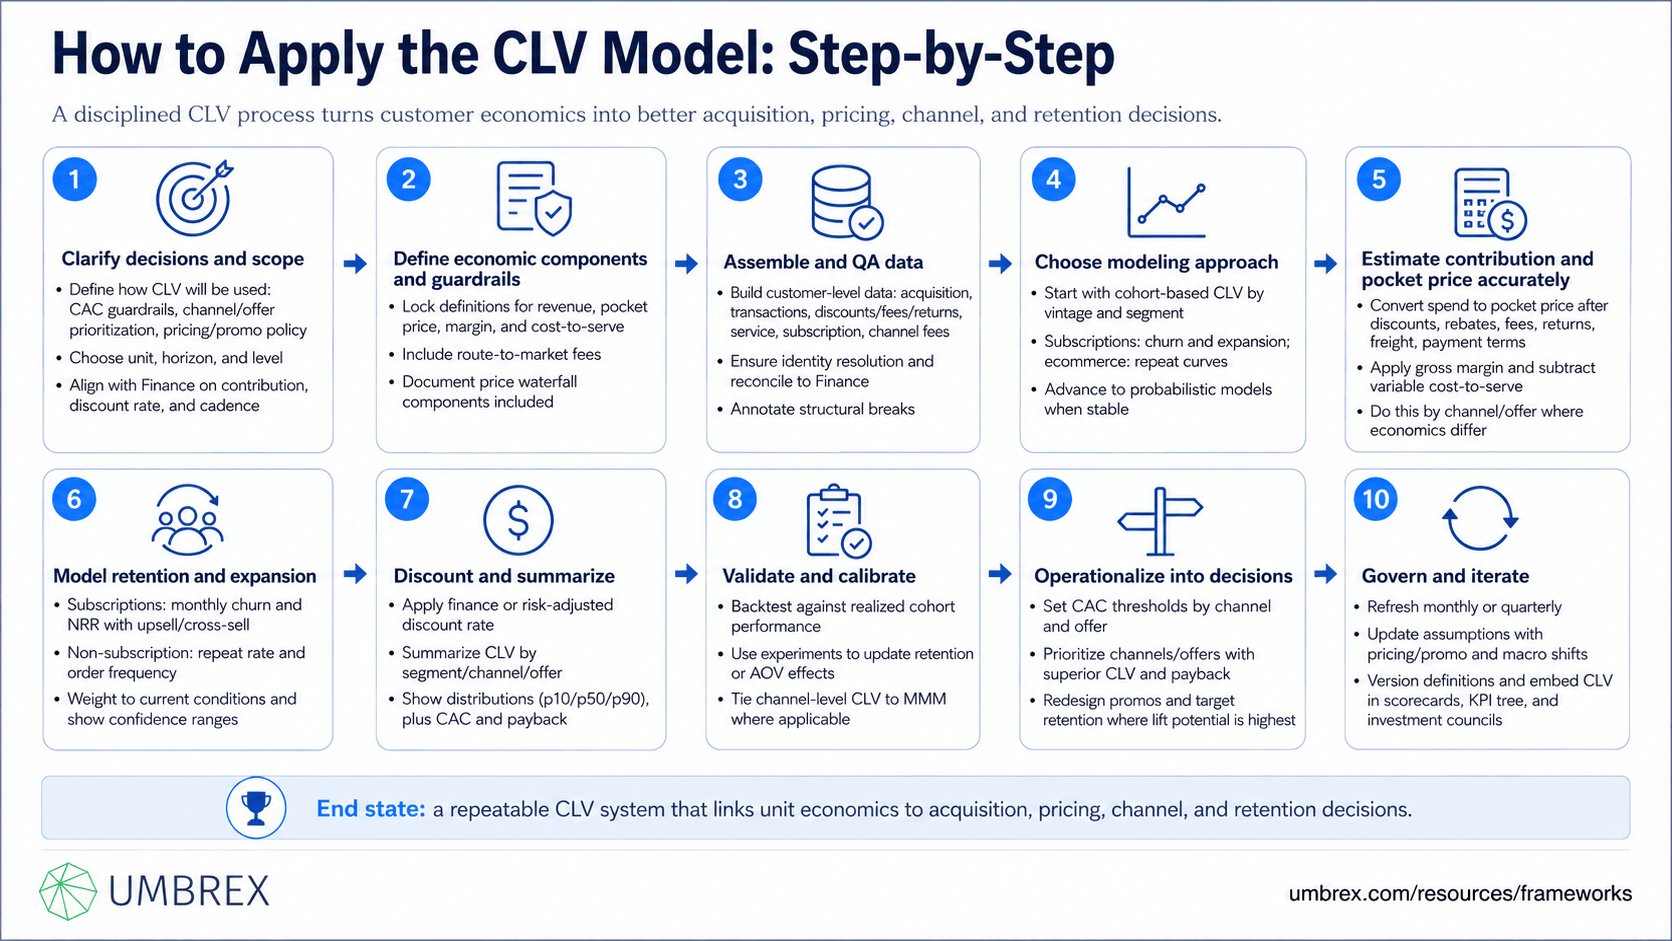
- Clarify decisions and scope
Define how CLV will be used: CAC guardrails? Channel/offer prioritization? Pricing/promo policy? Choose the unit (customer, account), time horizon, and level (segment/channel). Align with Finance on the economic basis (contribution, discount rate) and reporting cadence.
- Define economic components and guardrails
Lock definitions: revenue (gross vs pocket price), margin, cost-to-serve (COGS, shipping, payment fees, returns, support), and route-to-market fees (retail media, marketplace commissions). Document the price waterfall components included.
- Assemble and QA data
Build a customer-level dataset: acquisition date/source/offer, transactions with discounts/fees/returns, service interactions, subscription status, and channel fees. Ensure identity resolution is robust; reconcile totals to Finance; annotate structural breaks (pricing, onboarding).
- Choose modeling approach
Start with cohort-based CLV: compute retention/survival and spend per period by vintage and segment. For subscriptions, use churn/expansion rates; for ecommerce, use repeat purchase curves. Advance to probabilistic models (e.g., BG/NBD + Gamma-Gamma for spend) when stable.
- Estimate contribution and pocket price accurately
Convert spend to pocket price (list minus discounts, rebates, channel/marketplace fees, returns, freight, payment terms). Multiply by gross margin %, subtract variable costs to serve. Do this by channel/offer where economics differ materially.
- Model retention and expansion
For subscriptions, model monthly churn and net revenue retention (NRR) including upsell/cross-sell. For non-subscription, estimate repeat rates and order frequency. Use recent cohorts and weight toward current conditions; produce confidence ranges.
- Discount and summarize
Apply a discount rate (finance or risk-adjusted) to future contributions. Summarize CLV by segment/channel/offer and produce distributions (p10/p50/p90), not just averages; report CAC and payback alongside.
- Validate and calibrate
Backtest CLV predictions against realized cohort performance. Use experiments (e.g., onboarding, promo structures) to estimate causal lifts in retention or AOV and update the model. Tie channel-level CLV to MMM-driven channel effects where applicable.
- Operationalize into decisions
Set CAC thresholds (e.g., CLV/CAC ≥ 3.0 for paid social; ≥ 2.0 for affiliates given higher returns). Prioritize channels and offers with superior CLV and payback; redesign promos (favor fenced bundles vs deep discounts) where CLV evidences better pocket price and retention. Target retention programs to segments with the highest CLV lift potential.
- Govern and iterate
Refresh CLV monthly/quarterly; update assumptions with pricing/promo changes and macro shifts; version definitions. Embed CLV in your Marketing Balanced Scorecard and KPI tree; use it in quarterly investment councils with Finance.
6. Example: CLV in Action
Company: “EverGround,” a $400M omnichannel coffee brand selling via D2C subscriptions, marketplaces, and grocery retail.
Problem: New customer growth was strong, but contribution missed plan; pocket price fell 100 bps due to deep sitewide promos and marketplace coupon leakage. Acquisition shifted to affiliates and marketplace ads, with rising CAC.
Approach:
- Scope: Compute cohort CLV by acquisition source (paid social, search, affiliates, marketplace ads, D2C organic) and first-offer (sitewide discount vs member-only bundle with single-use codes). Time horizon 12 months for non-subscribers, 24 months for subscribers.
- Economics: Pocket price via price waterfall (discounts, marketplace commissions, retail media fees, returns, freight); contribution = pocket price × margin − variable costs (fulfillment, payment fees, support).
- Retention/expansion: Subscription churn and NRR modeled by cohort; ecommerce repeat rates estimated via cohort curves.
Findings:
- Affiliate + sitewide discount cohorts showed higher initial AOV but 20–25% lower 12-month contribution per customer; payback > 9 months; higher return rates.
- Paid social + member-only bundle cohorts had similar Month-0 volume with pocket price +90–120 bps; 12-month contribution +16%; payback 5–6 months.
- Marketplace ad cohorts suffered from coupon stacking and fees, producing CLV ~30% lower than D2C bundle cohorts despite attractive attributed ROAS.
- Onboarding content A/B increased 3-month retention by 5 pts in subscriptions; projected CLV +8–10%.
Decisions: Cut affiliate budget 35% and enforced single-use codes; reduced sitewide promos in favor of fenced bundles; shifted spend to paid social creatives driving bundles; set CAC thresholds by source (e.g., CAC ≤ $45 for paid social; ≤ $28 for affiliates given lower CLV); coordinated retail media bursts with launches and tighter promo rules.
Results (two quarters): Blended CAC payback improved from 8.0 to 5.9 months; pocket price +110 bps; 12-month cohort CLV +12% for recent vintages; MMM corroborated margin-accretive reallocation; ROMI rose from 1.18 to 1.52.
7. Strengths and Limitations
Strengths
- Finance-grade relevance: Ties growth to contribution, cash, and valuation; enables rational CAC guardrails.
- Channel/offer comparability: Reveals the true unit economics by route and promotion type, net of fees and returns.
- Actionability: Directly informs acquisition mix, pricing/promo design, onboarding, and retention investments.
- Forecastability: Cohort CLV curves project cash flows and payback credibly for planning.
Limitations
- Not inherently causal: CLV describes and predicts; experiments establish what drives improvements.
- Data heavy: Requires reliable identity, transaction, and cost data; poor pocket price modeling misleads.
- Assumption-sensitive: Small errors in churn, discounting, or returns compound across time; report ranges, not single points.
- Lagged feedback: In long cycles, improvements take time to show; use leading indicators cautiously and validate later.
8. Common Pitfalls (and How to Avoid Them)
- Revenue-only CLV
What goes wrong: Overstates value; ignores margin, fees, returns.
How to avoid: Use contribution and pocket price via the price waterfall; subtract variable costs-to-serve. - Average-only thinking
What goes wrong: One “average CLV” hides segment/channel differences; misallocates spend.
How to avoid: Report distributions and segment by channel, offer, product, and cohort; set CAC by segment. - Attribution bias
What goes wrong: Channels with low incrementality look good (e.g., affiliates) and get overfunded.
How to avoid: Pair CLV with experiments and MMM; treat channel CLV in context of incrementality. - Static assumptions
What goes wrong: CLV ignores pricing/promo changes, macro shifts, or onboarding updates.
How to avoid: Refresh monthly/quarterly; annotate major changes; backtest predictions. - Ignoring cost-to-serve heterogeneity
What goes wrong: High-return or support-intensive segments look equally valuable.
How to avoid: Include returns, support tickets, shipping zones, and payment fees by segment. - Confusing potential with realized
What goes wrong: Treats willingness-to-pay estimates or survey intent as CLV.
How to avoid: Base CLV on observed behavior; use surveys only as inputs to hypothesis tests. - No governance
What goes wrong: Teams debate numbers; definitions drift.
How to avoid: Publish a CLV glossary and version changes; reconcile to Finance; set an owner and cadence.
9. How the CLV Model Relates to Other Frameworks
- Cohort Analysis: CLV is best estimated on cohort curves; cohorts reveal how onboarding, offers, and channels change retention and monetization.
- ROMI (Return on Marketing Investment): Channel- or campaign-level CLV turns into CAC/LTV and payback; ROMI converts incremental lifts into finance-grade returns.
- Marketing Mix Modeling (MMM): MMM guides budget allocation and estimates channel effects; CLV ensures those allocations create durable value and acceptable payback.
- Attribution Modeling: Provides tactical signals; CLV prevents optimizing to non-incremental, low-value segments or channels.
- Price Waterfall & Promotional Mechanics: CLV must reflect pocket price, returns, and fees; promo structures (e.g., fenced bundles) often yield higher CLV than deep discounts.
- Brand Tracking Funnel & SOV–SOM: Gains in consideration/preference should translate into better retention and CLV; use MMM and cohorts to validate.
- Test-and-Learn (A/B, MVT): Experiments that improve onboarding, pricing, or UX should show higher CLV in subsequent cohorts.
- ABM / KAM (B2B): Account-level CLV connects pipeline to renewal/expansion economics; informs coverage and pricing strategies.
10. Key Takeaways
- CLV (Customer Lifetime Value) is the present value of future contribution from a customer after costs-to-serve—use pocket price, not gross revenue.
- Build CLV on cohorts; segment by channel and offer; produce distributions and payback, not single averages.
- Use CLV to set CAC guardrails, shape channel mix, design promotions and price fences, and target retention/onboarding investments.
- Refresh and validate with experiments and MMM; report uncertainty and backtest predictions; govern definitions with Finance.
- CLV links marketing and product to cash and margin; used well, it raises growth quality and enterprise value.
11. FAQs About the CLV Model
Should CLV be revenue-based or margin-based?
Margin-based (contribution) is the standard for decisions. Revenue-only CLV overstates value and can lead to destructive CAC and promo choices. Include pocket price and variable costs-to-serve.
What CLV/CAC ratio should we target?
Context-specific. Many firms target CLV/CAC ≥ 3.0 for paid channels, with faster payback (≤ 6–12 months) in cash-constrained settings. Use channel-specific thresholds grounded in your CLV distributions and risk tolerance.
How do we handle discount rates?
Use Finance’s WACC or a pragmatic risk-adjusted monthly rate (e.g., 0.8–1.5% per month). Report undiscounted and discounted CLV for transparency; be consistent across time and segments.
Can small or early-stage companies use CLV?
Yes—start simple: cohort retention and contribution over 6–12 months, segmented by channel/offer. Add sophistication (probabilistic models, expansion) as data matures; always reconcile to Finance.
How does CLV work for marketplaces/retail?
Include marketplace commissions, retail media fees, returns, and buy-box effects in pocket price. Segregate CLV by route (D2C vs marketplace vs retail) and set CAC and promo guardrails accordingly.
How often should we refresh CLV?
Monthly for high-velocity businesses, quarterly otherwise. Refresh assumptions after material pricing/promo or onboarding changes, and backtest predictions against realized cohort outcomes.
What if we don’t know long-term retention yet?
Use shorter-horizon CLV (e.g., 6–12 months) with confidence bands; extrapolate cautiously using analog cohorts; prioritize experiments that improve early retention, then update CLV as cohorts mature.
How do we keep CLV from becoming “one number to rule them all”?
Treat CLV as a decision tool, not a trophy metric. Pair with incrementality (experiments/MMM), maintain segment/channel cuts, include uncertainty, and ensure price waterfall alignment so decisions reflect true economics.
