
Goal of the analysis:
To identify distinct customer segments within the retail bank’s customer base and assess the penetration of specific banking products across these segments, enabling targeted marketing strategies and improved cross-selling opportunities.
Data required:
- Customer demographics (age, income, occupation, education level, etc.).
- Account information (account types, balances, transaction frequency).
- Product usage data (loan products, credit cards, savings accounts, investment products).
- Transaction data (spending patterns, average transaction size).
- Behavioral data (digital banking usage, engagement with offers, customer service interactions).
Detailed step-by-step instruction on how to conduct the analysis:
- Data Collection
- Extract relevant customer demographic and transactional data from CRM systems and banking databases.
- Ensure data accuracy and completeness by cleaning and validating datasets.
- Segment Creation
- Use clustering techniques (e.g., k-means clustering or hierarchical clustering) to group customers based on shared attributes such as demographics, behaviors, and product usage.
- Identify key segments such as “High-Value Customers,” “Young Professionals,” “Retirees,” etc.
- Product Penetration Analysis
- Calculate product penetration rate for each segment using the formula:
Product Penetration Rate = (Number of Customers Using Product / Total Customers in Segment) x 100 - Compare penetration rates across segments for each product.
- Calculate product penetration rate for each segment using the formula:
- Gap and Opportunity Identification
- Identify products with low penetration in specific segments but high potential for adoption based on segment characteristics.
- For example, if “Young Professionals” have a low penetration of investment products, this signals a growth opportunity.
- Behavioral Insights
- Analyze transaction and interaction data to uncover preferences, spending habits, or service needs unique to each segment.
- Action Plan Development
- Recommend tailored marketing and product bundling strategies for each segment based on identified gaps and preferences.
Format of the output of analysis:
- A segmentation table showing customer groups, their size, and key attributes.
- A penetration matrix indicating product usage rates by segment.
- Visual charts (e.g., bar charts, heatmaps) highlighting product gaps and opportunities.
- A summary report with actionable recommendations for increasing product penetration.
How to interpret results:
- High penetration rates indicate strong alignment between the product and the segment’s needs.
- Low penetration rates suggest untapped opportunities or misalignment with segment preferences.
- Segment-specific behaviors (e.g., high digital banking use) can guide targeted initiatives.
- Trends in cross-segment comparisons may reveal broader product development opportunities.
Steps a company can take to improve on this measure:
- Develop tailored marketing campaigns for low-penetration segments, emphasizing the benefits of underutilized products.
- Design product bundles appealing to specific segments (e.g., credit cards and savings accounts for “Young Professionals”).
- Train relationship managers to cross-sell and upsell effectively by understanding segment-specific needs.
- Leverage digital channels to promote products to tech-savvy segments, using personalized offers.
- Continuously refine segmentation and strategies using updated data and advanced analytics tools.
Request the PDF Download of How to Analyze a Retail Bank
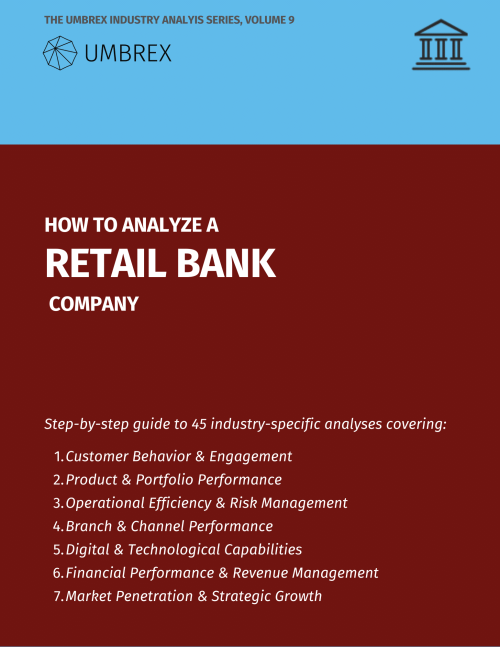
Menu of 45 analyses:
Table of Contents
A. Customer Behavior and Engagement
- Customer Segmentation and Product Penetration Opportunities
- Customer Satisfaction and Net Promoter Score (NPS)
- Cross-Selling and Up-Selling Effectiveness
- Customer Lifetime Value (CLV) and Acquisition Cost
- Customer Journey Mapping and Experience Optimization
- Customer Demographics and Financial Behavior
- Personal Financial Management Tool Engagement
- Customer Financial Health and Credit Utilization
- Customer Segment Profitability and Risk Assessment
- Customer Retention and Dormant Account Reactivation Strategy
- Debit and Credit Card Rewards Program Engagement
- Customer Support and Resolution Time Efficiency
B. Product and Portfolio Performance
- Retail Deposit and Loan Portfolio Performance
- Mortgage Portfolio Risk and Valuation
- Savings and Investment Account Tenure
- Loan Portfolio Diversification and Sectoral Risk Exposure
- Mortgage Loan-to-Value (LTV) and Debt-to-Income (DTI) Ratio
- Debt Consolidation Product Demand and Risk
- Loan Repayment Behavior and Default Management Strategy
C. Operational Efficiency and Risk Management
- Risk and Compliance Adherence for Retail Banking Operations
- Credit Quality and Loan Loss Provisioning
- Fraud Detection and Prevention Effectiveness
- Loan Origination and Underwriting Efficiency
- Operational Efficiency and Cost-to-Income Ratio
- Regulatory Compliance Cost
- Regulatory Capital Adequacy and Stress Testing
D. Branch and Channel Performance
E. Digital and Technological Capabilities
F. Financial Performance and Revenue Management
G. Market Penetration and Strategic Growth Opportunities
- Financial Inclusion and Market Penetration
- Deposit Growth and Stability
- Wealth Management and Investment Product Penetration
- Fee Income and Revenue Dependency
- Payment Services Usage and Revenue
- Personalized Banking Services Uptake and Impact
- Household-Level Financial Product Cross-Holdings
- Retail Banking Product Lifecycle and Attrition
- Loan Prepayment and Refinance Behavior
- Household Wealth Accumulation Trends
- Strategic Growth and Market Expansion Planning
