

1. What Is the Balanced Scorecard?
The Balanced Scorecard (BSC) is a strategy execution framework that translates an organization’s strategy into a concise set of objectives, measures, targets, and initiatives across multiple perspectives—not just financial results. It creates a clear line of sight from the strategy to what people do every day, enabling leaders to monitor progress, balance short- and long-term priorities, and adjust as conditions change.
Practically, the BSC organizes performance around four perspectives that collectively describe how value is created:
- Financial: How we create value for shareholders or owners.
- Customer: How we win with our target customers and stakeholders.
- Internal Processes: What we must excel at operationally to deliver the strategy.
- Learning & Growth (Organizational Capacity): How we build capabilities—people, culture, data, and technology—to sustain performance.
Within the Project Management function under “Portfolio, Strategy & Governance,” the Balanced Scorecard is a strategy and performance management framework. It is widely used by executives, boards, and consultants to align the enterprise, focus investment, and manage execution with evidence rather than opinion.
2. Origin and Background
The Balanced Scorecard was created by Robert S. Kaplan and David P. Norton. It was introduced in Harvard Business Review (1992) and elaborated in subsequent articles (1993) and the book “The Balanced Scorecard: Translating Strategy into Action” (1996). Kaplan and Norton later advanced the method with “The Strategy-Focused Organization” (2000) and “Strategy Maps” (2004), emphasizing cause–effect linkages and enterprise alignment.
The BSC emerged to solve a recurring problem: traditional performance systems overemphasized financial results—lagging indicators—while ignoring the drivers of future performance (customers, processes, and capabilities). By balancing these perspectives, the BSC provided a practical way to execute strategy, not just report history. It became widely known through academic publications, practitioner handbooks, and adoption across private and public sectors globally.
3. How the Balanced Scorecard Works
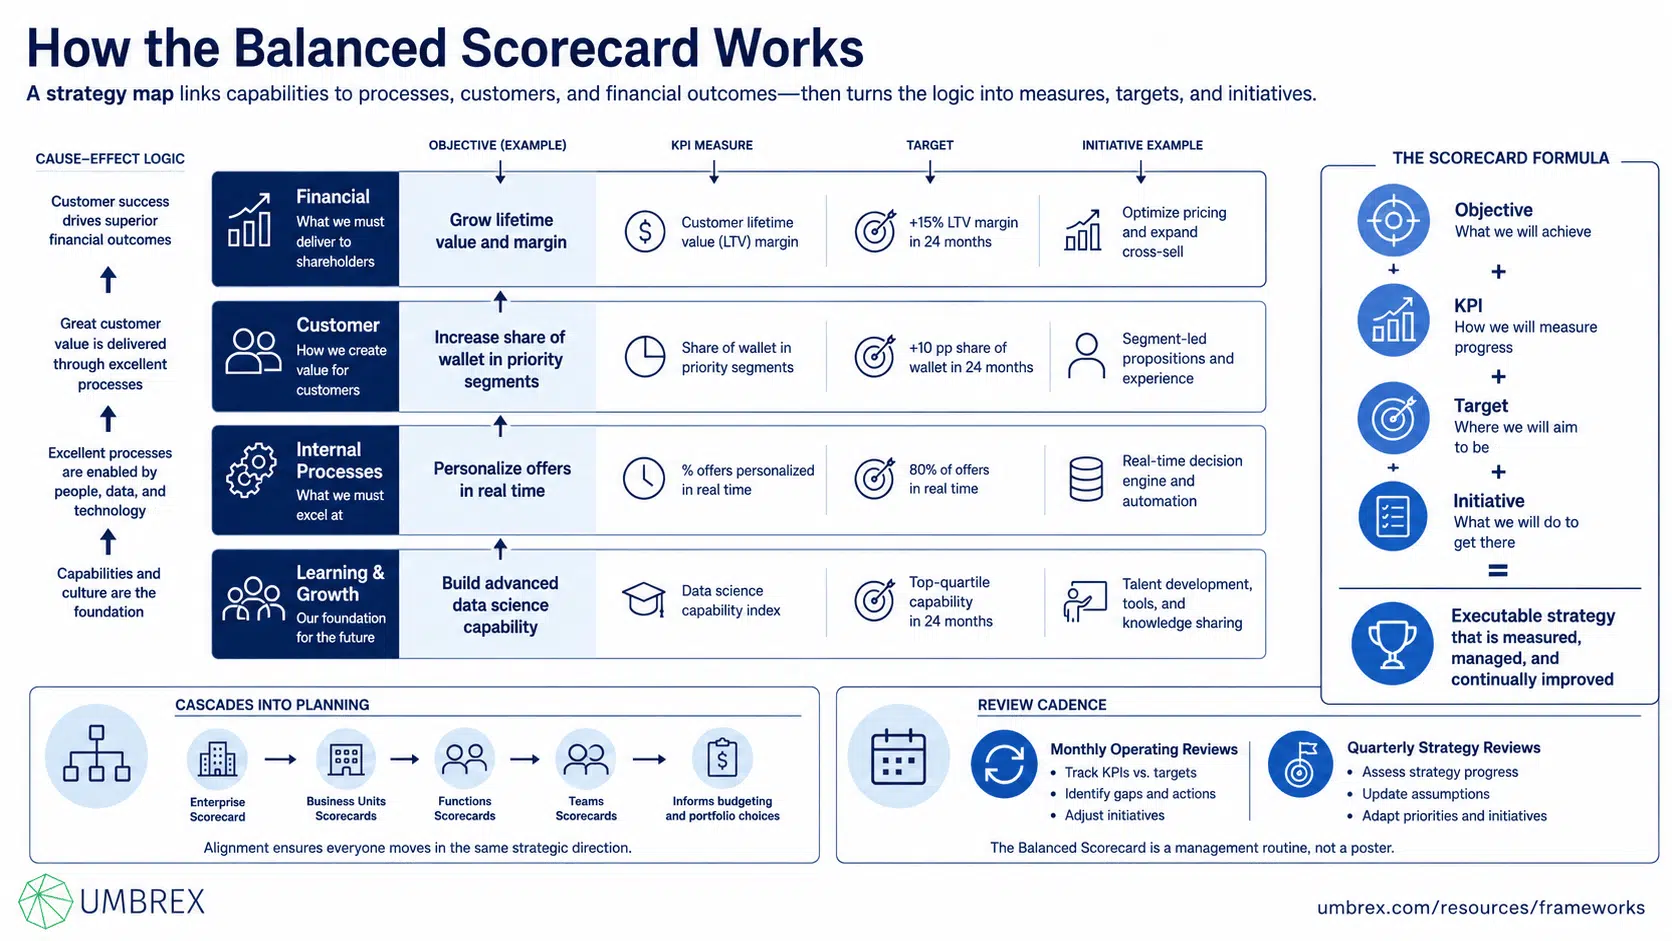
The BSC’s core logic is simple: articulate the strategy clearly, express it as a small set of cause–effect objectives across perspectives, define measures and targets for each objective, and mobilize initiatives to close the gaps. Review performance regularly, learn, and adapt.
Perspectives and Strategy Logic
- Learning & Growth → Internal Processes → Customer → Financial: Capabilities (skills, culture, data, technology) enable critical processes; superior processes deliver a compelling customer value proposition; customer success drives financial outcomes.
- Strategy themes and hypotheses: The BSC captures your strategic choices (e.g., operational excellence, customer intimacy, innovation leadership) as hypotheses that can be tested with data and refined over time.
Strategy Map (the backbone)
A strategy map is a one-page visual showing strategic objectives in each perspective and the cause–effect links among them. For example:
- Learning & Growth: “Build advanced data science capability.”
- Internal Processes: “Personalize offers in real time.”
- Customer: “Increase share of wallet in priority segments.”
- Financial: “Grow lifetime value and margin.”
Arrows connect capability → process → customer → financial, making the logic explicit and executable.
Objectives, Measures, Targets, Initiatives
- Objectives: Clear, action-oriented statements (e.g., “Reduce cycle time for claims adjudication”).
- Measures (KPIs): A mix of leading (drivers) and lagging (outcomes) indicators for each objective (e.g., straight-through-processing rate, average handling time, claim accuracy).
- Targets: Ambitious but realistic outcomes with a timeframe (e.g., “STP 70% by Q4”).
- Initiatives: Projects and programs that close performance gaps (e.g., rules engine modernization, training, process redesign).
Cascading and Alignment
- Cascaded scorecards: Enterprise BSCs cascade to business units, functions, and teams—each aligning local objectives and measures with the enterprise map while allowing context-specific nuance.
- Integration with planning: The BSC informs budgeting and portfolio choices; initiatives are selected and sequenced to move the measures toward targets.
- Governance cadence: Monthly reviews for operating metrics, quarterly strategy reviews for structural pivots. The BSC becomes a management routine, not a poster.
4. When to Use the Balanced Scorecard

The BSC is most valuable when you must translate strategy into execution across multiple teams, avoid KPI sprawl, and balance short-term performance with capability building.
- Company types: Mid-to-large enterprises; multi-business or multi-region organizations; public-sector agencies and nonprofits seeking mission-to-metrics clarity.
- Use cases: Strategy refresh and execution, turnaround or performance improvement, post-merger alignment, digital and data-enabled transformations, public-sector outcomes management.
- Data/time needs: Moderate. You need accessible operational and customer data, plus the discipline to review and act regularly. A first BSC can be built in weeks, refined over quarters.
Especially powerful when:
- Leaders want to shift from activity/output reporting to outcome-based management.
- Priorities compete and require explicit trade-offs across cost, growth, risk, and capability.
- You need a common language for strategy and performance across business and functional silos.
Less suitable or potentially misleading when:
- Early-stage startups are still seeking product–market fit; lightweight OKRs or hypotheses may be better until strategy stabilizes.
- Leaders expect a KPI dashboard to substitute for strategy—BSC clarifies and executes strategy; it does not create one from scratch.
- Organizations treat it as a compliance exercise; without decisions and resource shifts, it becomes shelfware.
Modern practice often pairs BSC with OKRs (for quarterly focus) and portfolio governance (for funding and sequencing), using the BSC as the stable “north star” and OKRs as the near-term steering wheel.
5. How to Apply the Balanced Scorecard: Step-by-Step

- Clarify the strategy and value logic.
Articulate strategic choices (where to play/how to win) and the few ways you will create value (e.g., customer intimacy, cost leadership, platform scale). This is the hypothesis your BSC will test and refine.
- Agree on perspectives and scope.
Use the classic four perspectives or adapt labels (e.g., “Organizational Capacity” for Learning & Growth). Define the enterprise scope first; cascading comes later.
- Build the strategy map.
Identify 12–20 strategic objectives across perspectives. Draw cause–effect links from capabilities → processes → customers → financials. Pressure-test with data and frontline insights. Keep it on one page.
- Define measures and targets.
For each objective, select 1–2 measures (ideally one leading, one lagging). Set baseline and target values with timeframes. Avoid vanity metrics; choose those you can influence and that track strategic progress.
- Prioritize initiatives to close gaps.
Identify the handful of initiatives that most move the measures. Use portfolio methods to prioritize and sequence under real capacity constraints; kill low-impact efforts.
- Cascade to units and functions.
Ask each business/function to create a local strategy map and scorecard aligned to enterprise objectives, with local measures and initiatives where sensible. Encourage fewer, better metrics.
- Integrate with planning, budgeting, and talent.
Align the budget to scorecard priorities; link incentives selectively to BSC outcomes (balanced mix of enterprise and local). Embed BSC objectives into role goals and development plans.
- Stand up data, dashboards, and cadence.
Instrument the measures, define data owners, and build simple dashboards. Establish monthly operating reviews (metric health, countermeasures) and quarterly strategy reviews (revisit hypotheses, reallocate resources).
- Review, learn, and adapt.
Track progress; diagnose variances; adjust initiatives and—when evidence dictates—the strategy map. Retire metrics that don’t inform decisions; add new ones only with intent.
- Communicate and coach.
Share the strategy map broadly. Train leaders in cause–effect thinking and metric literacy. Celebrate leading indicator wins (capability/process) as well as financial outcomes.
6. Example: Balanced Scorecard in Action
Context: A $5B regional bank needed to improve profitable growth while modernizing its core and raising digital adoption. Performance reporting was fragmented—dozens of dashboards, little linkage to strategy. The CEO launched a BSC to align priorities and funding.
Strategy map highlights:
- Financial: Improve risk-adjusted ROE; reduce cost-to-income by 400 bps.
- Customer: Lift primary relationship share in target households; raise NPS by 8 points in onboarding and servicing.
- Internal Processes: Increase straight-through processing (STP) for deposits and cards; cut onboarding cycle time by 50%; modernize credit decisioning.
- Learning & Growth: Build cloud/data platform capability; upskill frontline on needs-based conversations.
Measures and targets: ROE (lagging), cost-to-income (lagging); NPS by journey, digital adoption rate (leading), churn (lagging); STP rate, onboarding cycle time, decision turnaround (leading/lagging); cloud releases per month, model deployment cycle time, training completion (leading).
Initiatives: Core modernization sequenced in tranches; digital onboarding MVP; analytics-driven cross-sell; contact center enablement. The portfolio office used the BSC to prioritize funding and set WIP limits on the integration platform.
Outcomes (nine months): NPS +6 points in target journeys; digital adoption +14 points; STP for deposits reached 68% (from 42%); onboarding cycle time down 47%; cost-to-income improved by 180 bps; early signs of ROE lift in priority segments. Several low-impact enhancements were stopped; funds reallocated to scale the onboarding MVP. The bank institutionalized monthly BSC reviews and quarterly strategy resets.
7. Strengths and Limitations
Strengths
- Strategy-to-execution clarity: One-page strategy map and concise scorecard align leaders and teams.
- Balanced view: Mixes leading and lagging indicators across customers, processes, and capabilities—not just financials.
- Decision catalyst: Focuses initiatives and budgets on what moves the scorecard; exposes trade-offs and dependencies.
- Scalable and adaptable: Works across sectors (private, public, nonprofit) and cascades effectively.
Limitations
- Risk of KPI sprawl: Without discipline, metrics multiply and signal fades.
- Static bias: Annual maps can lag fast-moving markets unless paired with agile portfolio reviews.
- Implementation overhead: Data plumbing and cadence require leadership commitment; superficial rollouts underperform.
- Not a substitute for strategy: A clear strategy is prerequisite; BSC won’t fix strategic ambiguity.
8. Common Pitfalls (and How to Avoid Them)
- Too many objectives and metrics.
What goes wrong: Diffused focus; meetings become reporting rituals.
How to avoid: Cap the enterprise scorecard to ~15–20 objectives and ~20–30 metrics; prefer one leading and one lagging indicator per objective. - Lagging-only scorecards.
What goes wrong: You learn late and can’t course-correct.
How to avoid: Pair each outcome with drivers—capability, process, and customer behavior measures. - Confusing initiatives with measures.
What goes wrong: “Implement CRM” appears as a KPI; progress is activity, not impact.
How to avoid: Measures track outcomes; initiatives are how you move them. - No link to funding and capacity.
What goes wrong: Scorecard says one thing; budgets fund another.
How to avoid: Tie portfolio and budgeting decisions to scorecard gaps; stop low-impact work. - Weak cascade and accountability.
What goes wrong: Enterprise metrics don’t translate to teams; silo behavior persists.
How to avoid: Cascade maps/scorecards; assign owners; embed in role goals and incentives carefully. - Data ambiguity and gaming.
What goes wrong: Disputes over definitions; metrics optimized at the expense of outcomes.
How to avoid: Define metric owners and calculations; audit periodically; use multiple indicators to triangulate. - Set-and-forget cadence.
What goes wrong: Annual reviews ignore market shifts.
How to avoid: Monthly operating reviews; quarterly strategy resets with resource reallocation.
9. How the Balanced Scorecard Relates to Other Frameworks
- OKRs (Objectives and Key Results): OKRs drive near-term (quarterly) focus and stretch at team levels. The BSC provides the enduring strategy map and balanced measures. Many firms align OKRs to BSC objectives and use the BSC in executive reviews.
- Hoshin Kanri (strategy deployment): Hoshin emphasizes catchball and goal alignment. The BSC offers the structure for balanced measures; Hoshin provides the deployment process. They are complementary.
- Project Portfolio Management (PPM): PPM selects and funds initiatives. The BSC highlights where performance gaps are largest; PPM prioritizes initiatives to close them. Quarterly portfolio rebalancing pairs naturally with BSC reviews.
- Benefits Realization Management (BRM): BRM ensures initiatives deliver outcomes. The BSC defines strategic objectives and measures; BRM tracks realized benefits against those measures post-delivery.
- Value-Based Management (VBM): VBM focuses on economic value (e.g., EVA). The BSC broadens the lens to customer, process, and capability drivers that produce sustainable value.
- Quality/Operational frameworks (Lean, Six Sigma, TQM): These improve processes; the BSC ensures improvements align with strategic objectives and are reflected in balanced measures.
- EFQM/Baldrige: Excellence models assess organizational performance holistically. The BSC can serve as the operational scorecard within those frameworks.
10. Key Takeaways
- The Balanced Scorecard translates strategy into a small set of cause–effect objectives and measures across Financial, Customer, Internal Process, and Learning & Growth perspectives.
- Strategy maps make the value logic explicit; paired leading and lagging indicators enable course correction, not just reporting.
- Use the BSC to focus initiatives and budgets on the few things that matter; cascade to align teams and decisions.
- Keep it disciplined: fewer metrics, clear owners, defined data, and a monthly/quarterly cadence for learning and resource reallocation.
- Combine BSC with OKRs, PPM, and BRM to create a closed loop from strategy to funded work to realized outcomes.
11. FAQs About the Balanced Scorecard
Is the Balanced Scorecard still relevant today?
Yes. If anything, it’s more relevant amid digital transformation and data abundance. The BSC prevents KPI sprawl by focusing on the few drivers that link capabilities and processes to customer and financial outcomes, and it provides a sturdy backbone for OKRs and agile portfolio practices.
How is the BSC different from OKRs?
The BSC is a strategy execution system with balanced perspectives and enduring objectives/measures. OKRs are short-cycle goal-setting mechanisms. Use the BSC to define the strategic map and metrics; use OKRs to push quarterly progress on selected BSC objectives.
How many metrics should a good BSC include?
At the enterprise level, aim for roughly 20–30 measures across 12–20 objectives. Each objective should have 1–2 KPIs (ideally one leading, one lagging). More metrics dilute focus and signal.
How long does it take to implement?
A first-cut strategy map and scorecard can be built in 4–8 weeks with executive workshops and data baselining. Cascading, data plumbing, and embedding the cadence typically take 3–6 months, with ongoing refinement each quarter.
Can small and mid-size organizations use the BSC?
Absolutely—keep it light. Start with a one-page strategy map and ~10–15 measures. Review monthly, adjust quarterly, and avoid over-engineering data or tooling until the management routine is established.
Should incentives be tied to the BSC?
Selectively. Link a portion of variable pay to a balanced subset of BSC outcomes (enterprise and local) to encourage alignment without encouraging gaming. Emphasize learning and leading indicators, not just end-of-year financials.
